Mortgage Payoff Calculator - Extra Payment & Early Payoff Savings

Mortgage Payoff Calculator - Extra Payment & Early Payoff Savings

Calculate mortgage early payoff savings, loan term reduction, and interest saved with extra monthly, bi-weekly, or lump-sum payments. Client-side amortization schedule.

Strategy Presets:
Loan & Payment Parameters
$
%
30 Years (360 mos)
Accelerated
Extra Monthly Amount:
$
One-Time Lump Sum:
$
Interest Saved
$158,826
30% less interest
Term Shortened
7.7 Yrs
92 fewer payments
Debt-Free Date
Feb 2049
vs Oct 2056
Monthly Outlay
$2,894
Base $2,594
Loan Balance Payoff Decay Curves
Standard
Accelerated
$0k$100k$200k$300k$400kYr 0Yr 5Yr 10Yr 15Yr 20Yr 25Yr 30Free: Yr 22.3
Hover over chart to inspect annual balance differencesPrincipal reduction pace: +26% faster
Financial MetricStandard ScheduleAccelerated PlanNet Advantage
Monthly Base Payment (P&I)$2,594.39$2,594.39-
Extra Monthly Principal$0.00+$300.00Direct Principal
Total Monthly Outlay$2,594.39$2,894.39+$300/mo
Number of Payments360 mos268 mos-92 payments
Payoff Duration30 Years22.3 Years7.7 Yrs Earlier
Final Debt-Free DateOct 2056Feb 2049Fast-Forwarded
Total Interest Paid$533,981.26$375,154.87Save $158,826
Total Lifetime Loan Cost$933,981.26$775,154.87-$158,826
Home Equity Build Milestones
20% Equity (PMI Removal Threshold)
Month 95(vs Month 150)
Crossed 55 months earlier
50% Equity (The Tipping Point)
Month 181(vs Month 259)
Reached 78 months ahead
100% Free & Clear Ownership
Month 268(vs Month 360)
Saves 92 payments (7.7 yrs)
Base Monthly$2,594.39
Accelerated Outlay$2,894.39
Net Interest Saved$158,826
Term Reduction7.7 Yrs (92 mos)
Standard PayoffOct 2056
Accelerated PayoffFeb 2049
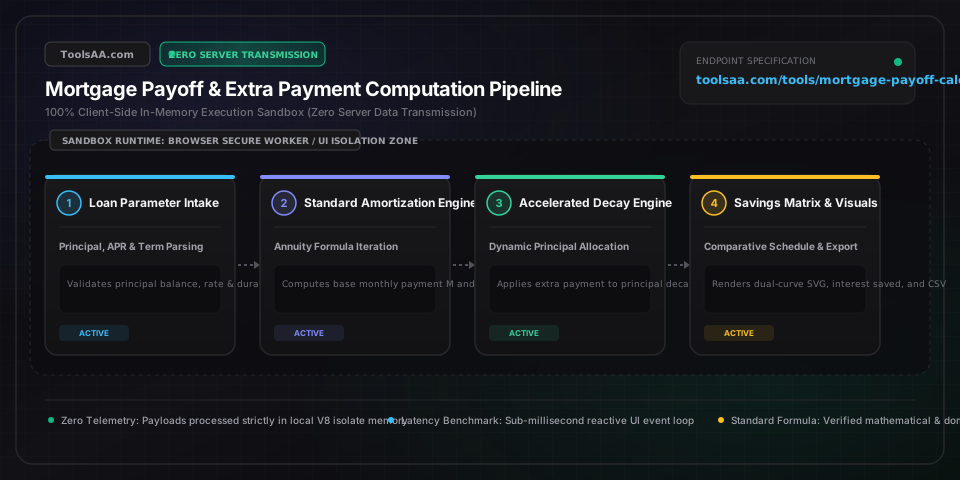
Technical Reference & Architecture Guide

Mortgage Payoff Calculator - Extra Payment & Early Payoff Savings — Reference Guide

Calculate amortization acceleration, cumulative interest savings, and payoff timeline reductions by making additional monthly or lump-sum principal payments on fixed-rate mortgages.

Mortgage Payoff Calculator - Extra Payment & Early Payoff Savings — Reference Guide — Client-Side In-Memory Architecture & Data Flow

Key Parameters & Controls

Loan Principal Amountnumber (USD / Currency)

Total original or outstanding principal mortgage balance remaining.

Default: 400000
Annual Interest Rate (APR)number (percentage)

Fixed annual nominal interest rate charged on the mortgage note.

Default: 6.75
Loan Termnumber (years)

Original or remaining amortization duration in years (e.g. 15 or 30).

Default: 30
Extra Monthly Paymentnumber (USD / Currency)

Additional monthly cash allocated directly toward reducing outstanding principal.

Default: 300
Payment Frequencystring (monthly | biweekly)

Repayment schedule cadence; accelerated bi-weekly yields 26 half-payments per year.

Default: monthly

Pro Tips & Best Practices

Ensure Payments Target Principal Directly

Verify with your loan servicer that additional remittances are coded explicitly as 'Principal Only' rather than prepaying future scheduled interest or escrow balances.

Accelerated Bi-Weekly Compounding Advantage

Paying half your monthly installment every two weeks produces 26 payments per year—equivalent to 13 full monthly payments, effortlessly cutting 4-6 years off a 30-year term.

Mortgage Recasting vs Early Payoff

If your primary financial objective is lowering required monthly overhead rather than early loan termination, inquire about mortgage recasting after deploying a major lump sum.

Common Gotchas & Troubleshooting

⚠️Extra Payment Does Not Reduce Scheduled Monthly Amount

In standard fixed-rate mortgages, extra principal payments accelerate the final payoff date rather than reducing the contractual monthly payment. To lower the monthly payment, ask your lender about a mortgage recast.

⚠️Penny Discrepancies with Lender Servicing Statement

Lending servicers compute per-diem interest based on 360-day or 365-day accounting conventions and exact calendar posting dates, causing minor nominal differences from idealized amortization formulas.

Frequently Asked Questions

How much interest do I save by paying an extra $300 a month on my mortgage?▼

On a $400,000 30-year fixed mortgage at 6.75%, paying an extra $300 every month saves approximately $78,500 in cumulative interest and pays off the entire loan 6 years and 4 months ahead of schedule.

What is the difference between extra monthly payments versus an annual lump sum?▼

Monthly prepayments start reducing the balance immediately, generating compounding interest savings every month. An annual lump sum is still effective but delays the compounding benefit compared to immediate continuous principal deployment.

Will my mortgage lender penalize me for prepaying my loan early?▼

Under US federal law (Dodd-Frank Wall Street Reform Act), almost all qualified residential mortgages (conventional conforming, FHA, VA, USDA) carry zero prepayment penalties. Always verify your loan disclosure documentation.

Is this mortgage payoff calculation legally binding or official financial advice?▼

Disclaimer: This mortgage payoff calculator is provided strictly for educational and informational purposes only and does not constitute formal financial advice, lending pre-approval, or a binding mortgage contract. Interest compounding rules, property taxes, escrow, PMI, and loan servicing fees may affect your actual payoff figures. Always consult a licensed mortgage loan officer or certified financial planner before making major prepayments.

Related Tools & Utilities

All Tools →