Hint housing
Hint utilities groceries
Hint debt insurance
Hint discretionary
Hint target months
Hint current savings
Hint yield apy
Cfa disclosure text
Calculate your optimal emergency fund target and survival runway across essential and discretionary expenses, life shock scenarios, and multi-tier liquidity vaults (Cash, HYSA, Government Bonds). Features bi-directional what-if reverse calculations and dynamic reserve allocation visualizers.
Hint housing
Hint utilities groceries
Hint debt insurance
Hint discretionary
Hint target months
Hint current savings
Hint yield apy
Cfa disclosure text
Calculate your optimal emergency fund target and survival runway across essential and discretionary expenses, life shock scenarios, and multi-tier liquidity vaults (Cash, HYSA, Government Bonds). Features bi-directional what-if reverse calculations and dynamic reserve allocation visualizers.
Incompressible living expenses (housing, staple groceries, essential utilities, minimum debt service) vs non-essential lifestyle spending.
Number of months a household can survive zero income without liquidating long-term investments or incurring high-interest debt.
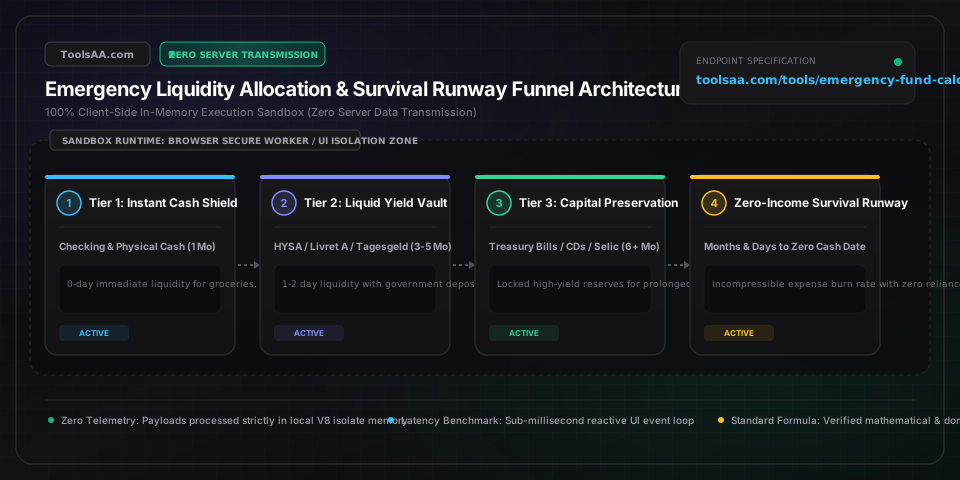
Strategic division between instant checking cash (1 month), high-yield savings (3-5 months), and short-term capital shields (6+ months).
Never size your emergency fund as 6 months of gross salary ($10k/mo salary = $60k fund). In an emergency, you do not pay income taxes or retirement 401(k) contributions, nor do you maintain luxury spending. An authentic emergency fund covers net incompressible expenses ($5k/mo = $30k fund), preventing $30,000 of unnecessary capital drag.
Holding a 6-month fund entirely in a zero-interest checking account loses $1,200 to $1,800 annually to a 4% inflation drag on a $35,000 balance. Keep only 1 month in checking for immediate debit card access; park 3-5 months in a government-guaranteed high-yield vehicle (HYSA, Livret A, Tagesgeldkonto) yielding 3.5%-5.0% APY.
Salaried employees with dual household incomes require 3 to 6 months of reserves. Solo entrepreneurs, commission-based sales professionals, and freelancers must target 9 to 12 months, as contract drying and client payment defaults frequently cluster during broader macroeconomic contractions.
Do not attempt to fund a 6-month reserve at once. Divide your journey into psychological micro-milestones: Milestone 1 is a $1,000 starter buffer to stop credit card reliance, Milestone 2 is 1 month of essential expenses, and Milestone 3 is 3 months. Automate 10-15% of every paycheck directly to a separate high-yield account.
In the US, never hold more than $250,000 per depositor per insured bank (FDIC). In the EU, statutory deposit insurance caps at 100.000 € (Einlagensicherung/FGD). In Japan, the deposit insurance cap is 1,000万円 (ペイオフ制度). When funds exceed these thresholds, sweep excess reserves across multiple independent financial institutions or short-term sovereign treasury bills.
Build a 1-month starter emergency fund ($1,500 - $3,000) first, then aggressively direct all surplus cash flow toward paying off high-interest debt (>12% APR). Carrying credit card balances at 24% APR while holding cash earning 4% guarantees a net financial loss of 20% annually.
No. During systemic economic recessions or personal job loss, financial institutions routinely freeze credit lines and slash borrowing limits without advance notice. Relying on debt as an emergency fund creates high risk of insolvency when access is revoked.
Legitimate emergencies meet three strict criteria: unexpected, non-negotiable, and urgent (e.g. sudden job loss, major vehicle engine failure, emergency medical procedure). Planned annual expenses like holiday gifts, routine car maintenance, and vacations must be budgeted separately in sinking funds.
Disclaimer: This tool is provided strictly for educational and informational purposes only and does not constitute formal financial advice or a binding loan commitment. Please consult a qualified financial advisor before making decisions. No. ToolsAA operates strictly in-browser via client-side JavaScript. All expense figures, savings balances, and runway calculations are processed purely in local browser memory and never transmitted over any network.
Calculate your true minimum viable and target hourly freelance rates based on desired net income, unbillable admin overhead, local self-employment taxes, and equipment expenses. Features bi-directional what-if reverse calculations and dynamic income waterfall charts.
Perform fraction arithmetic with mixed numbers, improper fractions, LCD finding, and step-by-step simplification. 100% private in-browser math cockpit.
Convert pressure units between PSI, Bar, Pascals (Pa, kPa, MPa), Standard Atmospheres (atm), Torr, and Millimeters of Mercury (mmHg) with visual gauge representation.
Calculate optimal bedtimes and wake-up times aligned with 90-minute ultradian sleep cycles (NREM/REM) to wake up refreshed without morning sleep inertia. 100% private in-browser health cockpit.
Calculate your ideal body weight (IBW) using consensus clinical formulas (Devine, Robinson, Miller, Hamwi) and healthy BMI bounds. 100% private in-browser health cockpit.
Spin the customizable decision wheel for prize giveaways, raffle drawings, classroom choices, and truth-or-dare picks with CSPRNG fairness and sound effects.