Lease Money Factor Calculator & APR

Badge captive finance•Tag standard2400

Lease Money Factor Calculator & APR

Convert lease money factors to equivalent APR, audit dealer worksheets for hidden rate markups, and calculate Multiple Security Deposit (MSD) savings with precision rent charge analytics.

Lbl quick scenarios

Title rate synchronizer

Badge multiplier2400
Badge standard5 dec
Badge annual rate
Lbl interactive rate slider0.00185 = 4.44% APR
0.00050 (1.20%)0.00200 (4.80%)0.00400 (9.60%)

Title cap cost residual

Lbl term months: 36 Unit months short
Lbl gross base
$
6.4% Lbl off
$
$31,350.00
%
Hint zero down recommended
$
Badge untaxed direct
$
Title fees and taxes
Lbl tax mode
Kpi total monthly payment
$764.72
$711.37 Lbl pre tax
Kpi equivalent apr
4.44%
Lbl short mf prefix: 0.00185
Kpi total rent charge
$5,514.15
$153.17/Unit months short
Kpi drive off due
$764.72
Lbl first month plus fees
Lbl monthly total$764.7236Unit months short
Title payment composition
Lbl depreciation portion$558.19 (73.0%)
Lbl rent charge portion$153.17 (20.0%)
Lbl tax portion$53.35 (7.0%)
Title mathematical formula auditTag verified arbitrary precision
Math formula adj cap$51,445.00
Math formula residual$31,350.00
Math formula deprec$558.19
Math formula rent$153.17
Title financial disclosures

Text disclosure1

Text disclosure2

Stat effective apr formulaAPR = MF × 2400
Stat total finance charge$5,514.15
Stat total lifecycle cost$27,924.83

Client-Side Processing

High-performance calculation executed entirely in browser memory.

Zero Server Upload Privacy

All payloads remain strictly local with zero external server communication.

Production Ready Export

Clean, optimized output formats ready for immediate deployment.
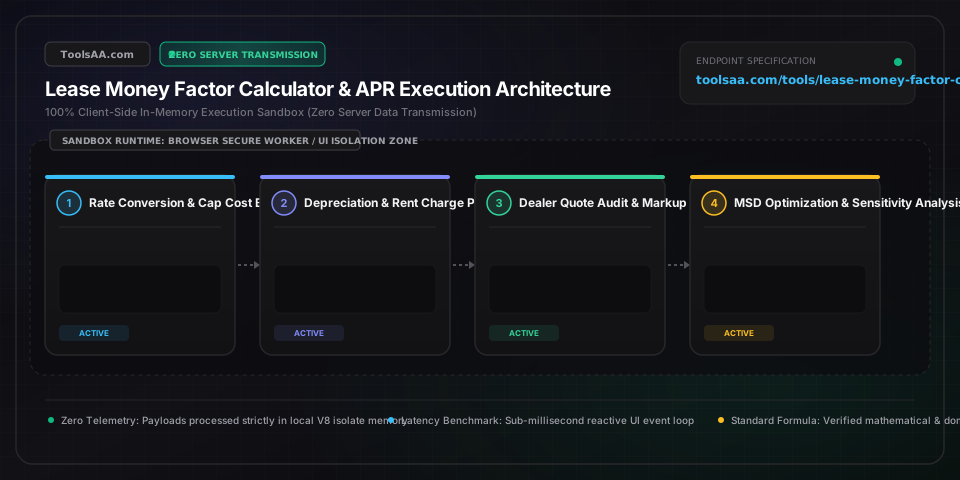
Technical Reference & Architecture Guide

Lease Money Factor Calculator & APR Guide

Convert lease money factors to equivalent APR, audit dealer worksheets for hidden rate markups, and calculate Multiple Security Deposit (MSD) savings with precision rent charge analytics.

Lease Money Factor Calculator & APR Guide — Client-Side In-Memory Architecture & Data Flow

Key Parameters & Controls

Money Factor (MF) / Lease Fee ConstantDecimal Fraction (0.00000 – 0.01000)

The fractional finance rate constant utilized by captive auto lenders. Multiplied by 2400 to derive equivalent nominal APR (e.g., 0.00200 = 4.80% APR). Super-prime tiers clear at 0.00140–0.00200, whereas near-prime and subprime financing exceeds 0.00280–0.00375.

Default: 0.00200
Contractual Residual Value (RV)Percentage of Monroney MSRP / USD

Fixed contractual purchase option set by the captive finance institution at lease inception, strictly pegged to the factory Monroney window sticker MSRP. Standard 36-month lease benchmark intervals range from 50% to 65% of MSRP.

Default: 58%
Adjusted Capitalized Cost (Net Cap Cost)Currency (USD / Net Financed Balance)

Total principal balance financed under the lease, representing agreed vehicle sales price plus capitalized acquisition and documentation fees, net of customer cap cost reduction and manufacturer lease cash rebates.

Default: $45,000
Multiple Security Deposit (MSD) UnitsInteger Count (0 – 9 Refundable Units)

Refundable cash collateral tranches pledged to captive lenders (such as BMW Financial Services or Toyota Financial Services) to shave 0.00004 to 0.00008 per deposit off the base money factor, generating 14% to 22% annualized tax-free internal rate of return (IRR).

Default: 7

Pro Tips & Best Practices

Zero-Down Capitalized Cost Reduction Rule

Never allocate upfront cash down payments toward capitalized cost reduction on an auto lease. Under standard captive gap coverage and total loss indemnification, the automotive insurer reimburses the leasing company actual cash value (ACV); any unamortized upfront cash equity is entirely forfeited. Retain liquidity in 4.5%+ APY high-yield cash equivalents instead.

Captive Buy Rate Audit Against Discretionary Dealer Markups

Request the captive finance institution's original rate approval sheet prior to signing. Dealerships routinely execute discretionary finance participation markups of up to 0.00040 (approx. 0.96% APR), which inflates monthly payments by $35–$50 on a $55,000 net cap cost and diverts $1,200–$1,800 into unearned dealership back-end reserve profit.

Tax-Free MSD Arbitrage vs. Taxable Fixed-Income Yields

Deploying 7 to 9 Multiple Security Deposits yields a contractual monthly payment reduction delivering a guaranteed 14% to 22% annualized ROI. Because lease expense reduction is classified as personal expense mitigation rather than taxable interest under IRS Form 1099-INT, its net economic yield matches a 20% to 33% pre-tax equivalent for filers in the 32%–37% federal tax brackets.

Monroney MSRP Residual Anchoring Verification

Audit the contract residual dollar figure to confirm it is derived strictly from the Monroney window sticker MSRP (including factory options and destination), never the negotiated vehicle sales price. If an F&I manager erroneously calculates residual percentage off a discounted selling price, monthly depreciation liability is artificially inflated.

Common Gotchas & Troubleshooting

⚠️Dealer Quoted Monthly Payment Discrepancy of $30–$60 Over Calculator Output

Audit the dealer worksheet for an unauthorized 0.00040 money factor markup, non-taxable drive-off fee roll-ins into gross cap cost, or capitalized dealer add-ons (nitrogen, paint protection). Use the reverse extraction formula: Implied Money Factor = (Base Monthly Payment - Monthly Depreciation) / (Adjusted Cap Cost + Residual Value) to isolate the hidden rate.

⚠️APR Disconnect When Using Standard 1200 Loan Constant Instead of 2400

Lease rent charges are computed against the combined sum of (Adjusted Cap Cost + Residual Value) rather than a standard declining balance. Because average capital exposure across the term equals (Cap Cost + Residual) / 2, dividing the annual rate by 12 months and dividing by 2 yields Rate / 24; converting percentage to decimal establishes the mandatory 2400 constant.

⚠️MSD Payment Reduction Mismatch on Dealer Contract Worksheet

Verify lender-specific security deposit rounding conventions: BMW Financial Services rounds each security deposit up to the nearest $50 increment based on the final post-tax monthly payment, whereas Toyota and Lexus Financial Services calculate rounding on pre-tax amounts. Ensure the exact per-deposit decrement (0.00006 vs 0.00008) matches current captive bulletin matrices.

Frequently Asked Questions

How to convert lease money factor to APR?▼

To convert a lease money factor to equivalent APR, multiply the money factor decimal by 2400 (APR = Money Factor × 2400). For example, a money factor of 0.00200 multiplied by 2400 equals 4.80% APR. Conversely, to determine the money factor from a quoted APR interest rate, divide the APR by 2400 (e.g., 6.00% APR / 2400 = 0.00250 MF).

Why is lease money factor multiplied by 2400 instead of 1200?▼

The 2400 conversion constant combines two distinct financial mechanics: converting an annual rate to a monthly rate (12 months) and calculating the average outstanding capital balance over the lease term ((Cap Cost + Residual Value) / 2). Dividing annual interest by 12 and dividing by 2 yields Rate / 24; incorporating the 100-multiplier percentage conversion establishes the universal 2400 denominator.

What is a good lease money factor for tier 1 credit?▼

A competitive tier 1 credit (FICO 740+) lease money factor ranges between 0.00140 and 0.00200 (equivalent to 3.36% to 4.80% APR) under non-subvented market interest rate regimes. Captive manufacturer subventions on targeted vehicle segments, promotional releases, or electric vehicle federal pass-throughs can further reduce promotional buy rates to 0.00030–0.00085 (0.72%–2.04% APR).

How do car dealers secretly mark up the money factor?▼

Captive finance companies assign approved wholesale 'buy rates' based on applicant credit tier, but grant franchise dealerships discretionary authority to mark up the rate by up to 0.00040 (approx. 0.96% APR) as dealer reserve profit. On a $60,000 financed balance over 36 months, an undisclosed 0.00040 markup inflates monthly payments by roughly $38, generating over $1,360 in back-end dealer revenue without federal Regulation M itemization mandates.

How do Multiple Security Deposits (MSDs) lower lease payments?▼

Multiple Security Deposits lower lease payments by reducing the contract money factor by a fixed decrement (typically 0.00004 to 0.00008) for each refundable deposit pledged at lease inception (up to 7–9 deposits). Pledging 7 MSDs on a luxury lease reduces the money factor by up to 0.00042 (approx. 1.01% APR), lowering monthly payments and producing an annualized, risk-free, 100% tax-exempt return of 14% to 22% on the escrowed collateral refunded upon lease termination.

What is the monthly rent charge formula in a car lease?▼

Disclaimer: This tool is provided strictly for educational and informational purposes only and does not constitute formal financial advice or a binding loan commitment. Please consult a qualified financial advisor before making decisions. The monthly rent charge formula is: Monthly Rent Charge = (Adjusted Capitalized Cost + Residual Value) × Money Factor. Unlike an amortizing installment auto loan where interest portions decrease each billing cycle as principal reduces, lease finance fees are uniformly levelized across the term by applying the fractional rate factor to the combined starting and ending capital balances.

Related Tools & Utilities

All Tools →