Tool title

Badge saa s metricsFormula brief

Rule of 40 Calculator (SaaS Growth & Margin)

Calculate your SaaS Rule of 40 score with revenue growth rate and profit margin. Benchmark against public SaaS multiples, solve target growth, and model FCF.

Lbl quick presets

Title model inputs

US-GAAP
+32.0%
%
+14.0%
%
40%
Lbl regime footnote header

US-GAAP baseline: ASC 606 revenue recognition, ASC 230 cash flow classification, and SEC CapEx capitalization treatment.

Lbl composite score
46.0%
Tier healthy32G + 14M
Lbl ev multiple
11.4x
Lbl range9.7x - 13.5x
Lbl enterprise valuation
$377,520,000
$33,000,000 Lbl arr ending
Lbl strategic tilt
Lbl tilt growth heavy
Lbl target gap+6.0%

Title visual stage

Desc visual stage

Lbl frontier40Lbl frontier50
-10%10%30%50%70%90%-40%-20%0%20%40%Lbl profit margin axisLbl revenue growth axisAnnot vc sweet spotAnnot pe sweet spot32%G / 14%M
Lbl metric breakdown title
Lbl gross margin row75%
Lbl nrr row110%
Lbl computed fcf row$4,620,000
Lbl valuation insight title

Desc healthy multiple

Stat1 label$33,000,000
Stat2 label46.0% (Tier healthy)
Stat3 label11.4x Lbl ntm revenue
Client-Side Processing

High-performance calculation executed entirely in browser memory.

Zero Server Upload Privacy

All payloads remain strictly local with zero external server communication.

Production Ready Export

Clean, optimized output formats ready for immediate deployment.

Disclaimer title

Disclaimer body
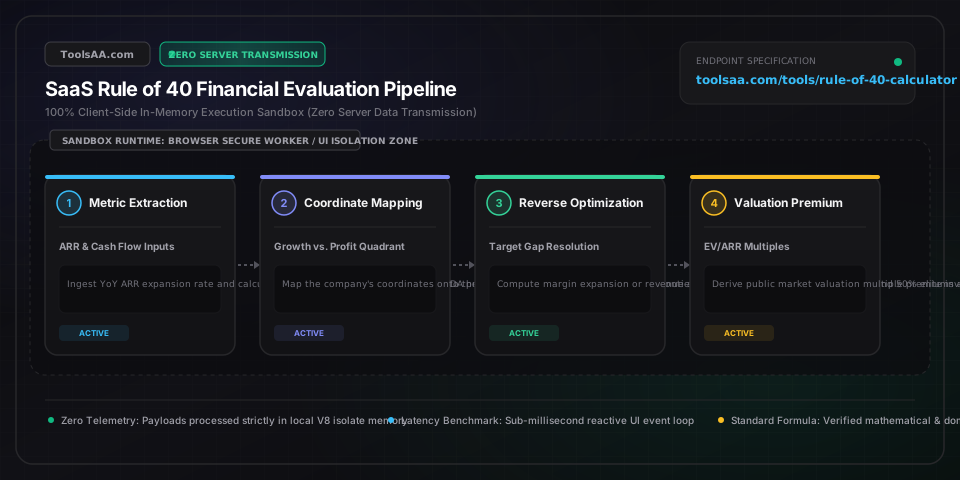
Technical Reference & Architecture Guide

Rule of 40 Calculator (SaaS Growth & Margin) Guide

Calculate your SaaS Rule of 40 score with revenue growth rate and profit margin. Benchmark against public SaaS multiples, solve target growth, and model FCF.

Rule of 40 Calculator (SaaS Growth & Margin) Guide — Client-Side In-Memory Architecture & Data Flow

Key Parameters & Controls

YoY Revenue Expansion RatePercentage (%)

Annual recurring revenue (ARR) or GAAP revenue percentage change over the prior twelve-month period. For early-stage companies, growth persistence typically decays by 15% to 20% annually.

Default: 32.0%
Free Cash Flow (FCF) MarginPercentage (%)

Operating cash flow less capital expenditures divided by revenue. Favored by private equity and public investors over EBITDA because it accounts for working capital drag and real cash burn.

Default: 14.0%
Adjusted EBITDA MarginPercentage (%)

Operating earnings before interest, taxes, depreciation, and amortization, often adjusted for non-cash share-based compensation. Beware of artificial score inflation from stock option dilution.

Default: 18.5%
Composite Rule of 40 ScoreBenchmark Index (%)

Sum of YoY revenue growth rate and profit margin. Institutional thresholds: >=50% (Top Decile / Premium Multiples), 40%-49% (Target Benchmark), 20%-39% (Discount Multiples), <20% (Distressed).

Default: 46.0%
Implied EV/ARR Valuation MultipleMultiple (x ARR)

Empirical enterprise value to annualized revenue multiple estimated from market regression curves. Companies exceeding the Rule of 40 historically command a 1.5x to 2.5x multiple premium over peers.

Default: 8.8x

Pro Tips & Best Practices

Beware the Stock-Based Compensation (SBC) EBITDA Trap

Many software executives calculate the Rule of 40 using Adjusted EBITDA that adds back massive stock-based compensation (often 15% to 25% of revenue). Institutional growth equity investors and acquirers strip out this distortion by utilizing Free Cash Flow Margin instead. A company reporting a 45% score on EBITDA might actually sit at an unhealthy 25% on FCF after accounting for real share dilution and CapEx.

Factor in the Growth Persistence Rate Decay Curve

Public SaaS financial data demonstrates that revenue growth rates decay by an average of 15% to 20% each year as the revenue base expands (e.g., a company growing at 60% this year typically grows at ~48% next year and ~38% the year after). If your profit margin does not expand by at least 10 to 12 percentage points annually to compensate for growth decay, your Rule of 40 score will steadily slip below the 40% barrier.

Net Retention Rate (NRR) Provides the Ultimate Structural Floor

A Rule of 40 score driven primarily by high gross customer acquisition cost (CAC) burn is fragile. Conversely, a company with a Net Revenue Retention (NRR) rate >120% enjoys an automatic 20% built-in baseline revenue growth from existing accounts before spending a single dollar on new customer acquisition, making a 40%+ score structurally defensible.

The Rule of 40 Cutoff Flips Around $15M to $20M ARR

For seed and early Series A startups (<$10M ARR), product-market fit and hyper-growth (>100% YoY) render the Rule of 40 largely meaningless because heavy upfront engineering and GTM investments cause extreme negative margins (-80% to -150%). The metric becomes a critical institutional gating factor once a business crosses $15M to $20M ARR on the path toward private equity buyout or IPO.

Common Gotchas & Troubleshooting

⚠️Annualized Quarterly Run-Rate (QoQ x 4) Distorting Growth Figures

Annualizing a single strong or weak quarter (e.g., multiplying sequential QoQ growth by 4) magnifies seasonality, contract renewal timing, and quarter-end sales spikiness. Always calculate revenue growth using Trailing Twelve Months (TTM) or Year-over-Year (YoY) ARR comparisons to eliminate seasonal volatility.

⚠️Confusing GAAP Operating Margin with Unlevered Free Cash Flow

GAAP operating margin includes non-cash depreciation and amortization expenses while ignoring upfront multi-year annual upfront cash collections (deferred revenue). Software businesses with strong annual contract billing often generate significantly higher FCF than operating income. Ensure consistency by selecting 'fcf_margin' when evaluating cash runway and solvency.

⚠️Reverse Goal Solver Demands Mathematically Unattainable Margin Targets

If your revenue growth has collapsed to low single digits (e.g., 5%), hitting a 40% score requires a 35% net profit margin—a milestone achieved by fewer than 5% of all software enterprises. In this regime, operational cost-cutting alone cannot restore top-tier valuation; management must reignite growth through product expansion or pricing adjustments.

Frequently Asked Questions

How do you calculate the SaaS Rule of 40 formula?▼

The Rule of 40 formula is calculated by adding your Year-over-Year (YoY) Revenue Growth Rate percentage to your Profit Margin percentage: Rule of 40 Score = Growth Rate (%) + Profit Margin (%). For example, if a SaaS company grows revenue at 30% YoY and generates an operating Free Cash Flow margin of 15%, its composite score is 45% (30% + 15%), successfully surpassing the 40% threshold.

What is considered a good Rule of 40 score for software companies?▼

A score of 40% is the institutional benchmark for healthy software performance, but top-decile SaaS companies frequently achieve 50% or higher. According to Bessemer Venture Partners and public cloud indices, companies scoring above 40% trade at an average 2x enterprise value to revenue multiple premium compared to companies scoring under 30%, which face steep valuation discounts and fundraising resistance.

Should I use EBITDA margin or Free Cash Flow margin for the Rule of 40?▼

Free Cash Flow (FCF) margin is the preferred institutional standard because it captures actual cash generated after capital expenditures, capitalized software, and changes in working capital. Adjusted EBITDA is commonly used in marketing decks, but it often inflates scores by ignoring non-cash stock compensation dilution and debt-service costs. Using FCF provides the most reliable indicator of financial self-sufficiency.

Does the Rule of 40 apply to early-stage startups under $10M ARR?▼

Disclaimer: This tool is provided strictly for educational and informational purposes only and does not constitute formal financial advice or a binding loan commitment. Please consult a qualified financial advisor before making decisions. No, the Rule of 40 does not reliably apply to early-stage software companies with under $10M ARR. Seed and Series A startups typically burn substantial capital building core products and validating go-to-market channels, leading to negative margins (-80% to -150%) that eclipse growth. Institutional venture capitalists prioritize triple-digit growth (>100% YoY), gross margin (>75%), and customer acquisition payback periods until the company scales past $15M to $20M ARR.

Related Tools & Utilities

All Tools →
Net Revenue Retention Calculator & NDRfinance

Professional SaaS Net Revenue Retention (NRR / NDR) and Gross Revenue Retention (GRR) intelligence calculator. Models customer cohort ARR/MRR dynamics including expansion upsells, contraction downgrades, and churn cancellations. Features an ARR movement waterfall bridge, SaaS Quick Ratio efficiency rating, 5-year compounding cohort decay projection, reverse expansion target solver, and sensitivity matrix benchmarked against top-decile BVP and OpenView SaaS standards.

Open tool→
Trench Drain Calculator (Runoff & Sizing)Utility

Calculate trench drain channel size, peak storm runoff (Q=CIA), Manning flow capacity, and outlet pipe diameter with imperial and metric engineering precision.

Open tool→
Roof Pitch Multiplier & Slope Factor Calcconstruction

Interactive Roof Pitch Multiplier & Rafter Slope Factor Calculator with real-time client-side analysis and visualization.

Open tool→
Post Hole Depth & Concrete CalculatorUtility

Calculate post hole depth, diameter, and concrete bags for fence posts, decks, and pergolas. Includes frost line depths, gravel drainage, and 1/3 rule sizing.

Open tool→
Pipe Insulation & Heat Loss CalculatorUtility

Calculate pipe insulation thickness, heat loss, and annual energy savings across copper, PEX, and steel pipes. Prevent condensation and freeze damage accurately.

Open tool→
Equipment Lease vs Buy & NPV Calculatorfinance

Enterprise-grade equipment lease vs buy financial evaluation engine. Computes after-tax Net Present Cost (NPC), Section 179 expensing, MACRS and international capital allowances, debt amortization schedules, terminal salvage recapture, and dual break-even solvers with dynamic sensitivity matrices.

Open tool→