Header title

Stat1 label|Lbl dimension range desc

Matrix Determinant Calculator & Step Solver

Calculate matrix determinants instantly with step-by-step LU decomposition, cofactor expansion, eigenvalues, and invertibility checks for 2x2 up to 8x8 matrices.

Lbl quick presets

Matrix editor title

1,1
1,2
1,3
2,1
2,2
2,3
3,1
3,2
3,3

Matrix editor hint

Kpi determinant1Status invertible
Kpi matrix trace1Lbl trace formula
Kpi matrix rank3 / 3Status full rank
Kpi condition number1.73Status well conditioned

Trace title

Trace desc

Lbl step counter 1 Lbl of 3
Badge step initialLbl parity sign +1

Step desc initial

1
0
0
0
0
-1
0
1
0
Lbl final det formula
det(A) = (-1) × [1 × 1 × -1] = 1
Stat1 labelStat1 value
Stat2 labelStat2 value
Stat3 labelStat3 value

Client-Side Processing

High-performance calculation executed entirely in browser memory.

Zero Server Upload Privacy

All payloads remain strictly local with zero external server communication.

Production Ready Export

Clean, optimized output formats ready for immediate deployment.
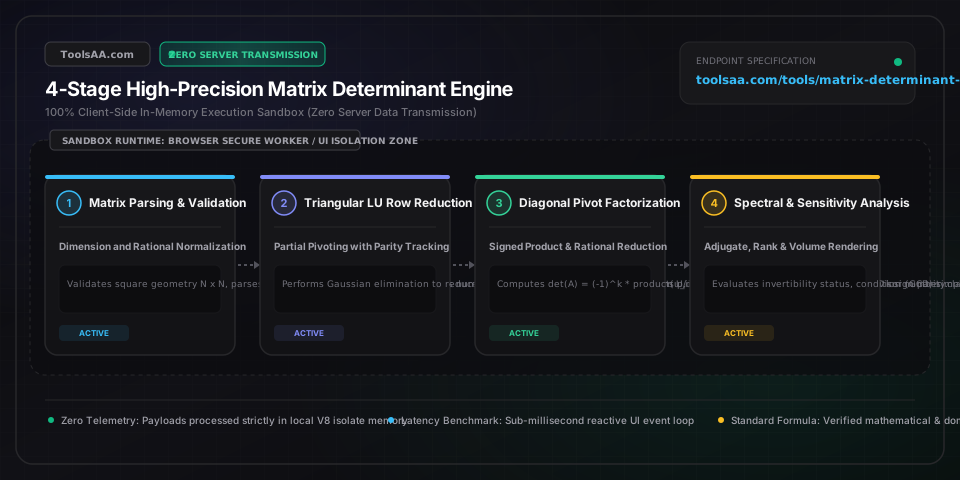
Technical Reference & Architecture Guide

Matrix Determinant Calculator & Step Solver Guide

Calculate matrix determinants instantly with step-by-step LU decomposition, cofactor expansion, eigenvalues, and invertibility checks for 2x2 up to 8x8 matrices.

Matrix Determinant Calculator & Step Solver Guide — Client-Side In-Memory Architecture & Data Flow

Key Parameters & Controls

Square Matrix Dimension Order (N × N Grid)Square Grid Dimension (2×2 to 8×8)

Defines the square grid order of the matrix system. Determinants are geometrically and algebraically defined strictly for square systems where equations match variables, spanning from elementary 2×2 coordinate planes up to 8×8 multi-variable systems commonly solved in physics and engineering.

Default: 3 × 3
Calculation Strategy & Decomposition MethodAlgorithm Choice (Auto | LU Decomposition | Laplace Cofactor | Sarrus Rule)

Selects the step-by-step solving path: LU decomposition with partial row pivoting scales efficiently in O(n³) operations for larger systems, Laplace cofactor expansion displays clear sub-matrix minor calculations ideal for exam step derivation, and Sarrus rule provides rapid diagonal evaluation for 3×3 grids.

Default: Auto
Numerical Precision & Exact Fraction ModePrecision Display (Exact Rational p/q | Decimal | Scientific | LaTeX)

Controls numeric accuracy. Exact rational representation uses symbolic integer arithmetic to preserve fractions without rounding distortion, while decimal and scientific modes display values rounded up to 64-bit IEEE 754 floating-point accuracy thresholds (15 to 17 significant figures).

Default: Exact Fractions (p/q)
Matrix Entry Coefficients A[i,j]Rational Scalar (Integer, Decimal, or Fraction p/q)

Individual scalar values positioned at row i and column j, representing coordinate projections or linear equation weights. Accepts positive and negative whole numbers, decimals, and exact fractional ratios (such as -7/3) forming the spatial vectors that define geometric volume.

Default: Identity Matrix

Pro Tips & Best Practices

Row Interchange Sign Inversion Rule

Swapping any two rows or columns inverts the geometric orientation of the vector space, multiplying the entire determinant by -1. When performing Gaussian row elimination, count the total number of row interchanges k: the final determinant equals (-1)^k multiplied by the product of the diagonal pivots.

Triangular & Diagonal Matrix Product Shortcut

Whenever all elements either above or below the main diagonal are zero (upper-triangular, lower-triangular, or diagonal matrices), you can skip all cofactor expansions. The determinant is simply the product of the main diagonal entries: det(A) = a11 * a22 * ... * ann.

Sparse Row Selection for Faster Cofactors

When calculating determinants by Laplace cofactor expansion by hand, always expand across the row or column containing the most zero entries. Because each zero eliminates an entire sub-matrix minor calculation, expanding along a sparse row often reduces a tedious multi-step problem to a single 2x2 determinant.

Multiplicative Scale Factor in Spatial Transformations

Determinants obey the multiplicative rule det(A * B) = det(A) * det(B). In geometric transformations and computer modeling, chaining multiple rotations, shears, and scales produces a net volume scaling factor equal to the product of each transformation's individual determinant, where a negative result signals a mirror-image spatial reflection.

Common Gotchas & Troubleshooting

⚠️Near-zero floating-point artifact (such as 1e-16 or 0.0000000000000002) instead of an exact zero

Switch the Numerical Precision Mode to 'Exact Fractions (p/q)'. Binary floating-point arithmetic (IEEE 754) introduces infinitesimal rounding noise during division pivots; exact rational arithmetic uses integer numerators and denominators to resolve singular matrices to true zero.

⚠️Matrix determinant computes to zero despite all individual cell entries being non-zero

Check for linear dependency between your rows or columns. If any row can be created by scaling or adding other rows (for example, Row 3 = 2 * Row 1 - Row 2), the vectors collapse into a flat subspace with zero geometric volume, rendering the determinant zero and the matrix non-invertible.

⚠️Matrix dimension error when pasting tabular values or LaTeX matrices

Ensure your pasted data represents an exact square grid where the total row count matches the total column count. While the parser cleans brackets, commas, and whitespace, determinants cannot mathematically exist for non-square rectangular matrices.

Frequently Asked Questions

How do you calculate the determinant of a 3x3 matrix without Sarrus rule?▼

To calculate a 3x3 determinant without Sarrus rule, use Laplace cofactor expansion along the first row: det(A) = a11(a22*a33 - a23*a32) - a12(a21*a33 - a23*a31) + a13(a21*a32 - a22*a31). Alternatively, use Gaussian elimination with partial pivoting to reduce the matrix into an upper-triangular form with zeros below the diagonal; the determinant then equals the product of the diagonal pivots multiplied by (-1)^k, where k is the number of row swaps performed.

Why is the determinant equal to zero for linearly dependent rows?▼

Geometrically, the determinant represents the signed hyper-volume spanned by the matrix's row or column vectors. When rows are linearly dependent, at least one vector lies within the geometric subspace spanned by the others (such as three 3D vectors lying flat on a 2D plane), collapsing the enclosed volume to zero. Algebraically, row reduction on linearly dependent equations produces an entire row of zeros, making the product of diagonal pivots zero.

How does Gaussian elimination affect the determinant during row operations?▼

Gaussian elimination alters determinants according to three fundamental rules: adding a multiple of one row to another leaves det(A) completely unchanged, swapping any two rows multiplies det(A) by -1, and scaling an entire row by a constant factor c multiplies det(A) by c. By using row addition and tracking row swaps without scalar row multiplication, the determinant equals (-1)^k times the product of the main diagonal entries of the resulting upper-triangular matrix.

What is the computational complexity difference between cofactor expansion and LU decomposition?▼

Laplace cofactor expansion has factorial time complexity O(N!), requiring 3,628,800 arithmetic steps for a 10x10 matrix and becoming practically impossible to compute for grids larger than 5x5. In contrast, Gaussian LU decomposition operates in polynomial time O(N^3), solving a 10x10 matrix in fewer than 1,000 arithmetic steps, which makes LU decomposition the standard algorithm for modern scientific and engineering calculations.

How do eigenvalues relate to matrix determinants and invertibility?▼

The determinant of any square matrix equals the exact product of all its eigenvalues: det(A) = λ1 * λ2 * ... * λn. A matrix is invertible (non-singular) if and only if det(A) != 0, which guarantees that zero is not an eigenvalue. If det(A) = 0, the matrix has a non-trivial null space, maps non-zero vectors to zero, collapses spatial volume, and cannot be mathematically inverted.

Related Tools & Utilities

All Tools →