Rent Vs Buy Calculator & Breakeven
Title control deck
USD ($)

US Conventional (SALT Cap & Sec 121 Exemption)

Sec purchase financing
$450,000
20%
$90,000
6.50%
3.0%7.0%12.0%
2.5%
$11,250
Sec recurring expenses
1.25%
$5,625/yr
$1,600
$150/mo
1.25%
$5,625/yr
Sec renting baseline
$2,500/mo
3.5%
$22/mo
Sec macro opportunity
4%
8%
24%
6%
Hint seller costs
10 Word years
1Y5Y10Y15Y20Y30Y
Badge renting winsLbl at year 10

Lbl renting builds lead +$37,545 Lbl more net wealth

Lbl no breakeven found

Card buyer at horizon (Y10)4.0% Lbl appreciation cagr
$320,949Lbl net liquidation equity
Lbl projected home val$666,110
Lbl remaining debt$305,194
Lbl total owner outflow$552,866
Lbl selling costs est$39,967
Card renter at horizon (Y10)8.0% Lbl equity cagr
$358,494Lbl compounded investments
Lbl monthly rent end10$3,407/mo
Lbl cumulative rent$357,399
Lbl initial capital$98,750
Lbl investment gains$259,744
Lbl cash flow dynamics
Lbl initial owner monthly$3,534/moP&I ($2,275) + Escrows
Lbl initial renter monthly$2,522/moRent + Renter Insurance
Lbl initial monthly delta$1,012/moLbl renter cash surplus
Lbl cfa verdict summary

Cfa rec no breakeven

Lbl stress challenger
Lbl breakeven horizon30+ Word years
Lbl net wealth advantage-$37,545
Lbl price to rent ratio15.0x
Lbl monthly p i$2,275/Word month
Lbl initial monthly outflow$3,496/Word month
Lbl down payment total$101,250

Disclaimer text

Technical Reference & Architecture Guide

Rent Vs Buy Calculator & Breakeven Guide

Compare renting versus buying a home with our rent vs buy calculator. Calculate the breakeven year, opportunity costs, home equity, and 30-year net wealth.

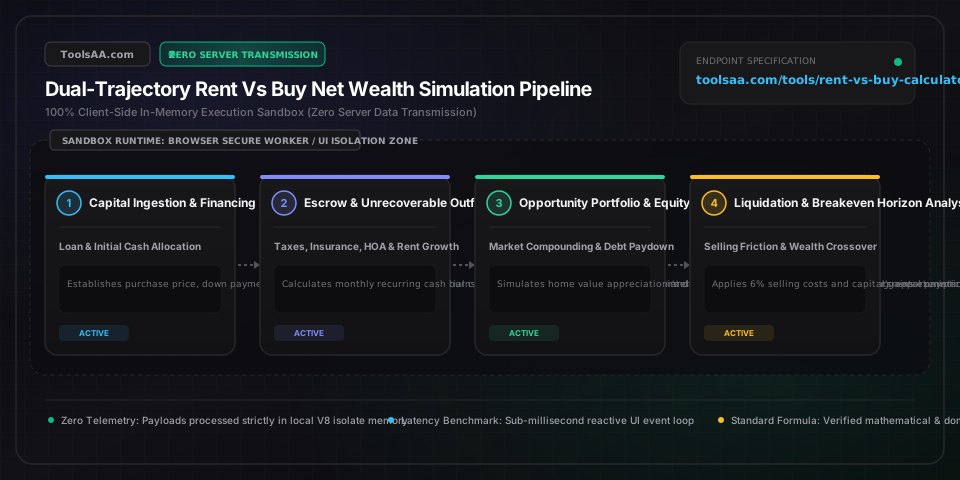
Rent Vs Buy Calculator & Breakeven Guide — Client-Side In-Memory Architecture & Data Flow

Key Parameters & Controls

Price-to-Rent Ratio (P/R Multiple)Market Valuation Ratio (Home Price ÷ Annual Rent)

A macroeconomic benchmark measuring housing market valuation. A ratio under 15 indicates purchasing is favored; 16 to 20 represents a neutral transition zone; above 21 signals that renting and investing surplus cash offers superior capital efficiency.

Default: 16.8
Unrecoverable Cost of Housing (5% Rule)Annual Cost Percentage (% of Home Value)

Calculates the unrecoverable dead-money cost of homeownership: approximately 1% property tax + 1% maintenance & repairs + 3% cost of capital (mortgage interest or equity opportunity cost). If equivalent rent is less than 5% of home price annually, renting is mathematically cheaper.

Default: 5.0%
Equity Opportunity Cost RateCompounded Annual Growth Rate (CAGR %)

The annual rate of return foregone by committing capital to a home down payment, closing costs, and monthly cash flow premiums rather than investing in a broad market index fund (e.g. S&P 500 historic real return of 7% to 10%).

Default: 7.5%
Capital Gains Home Sale Exclusion (IRS §121)Federal Tax Exemption Ceiling ($)

Under United States tax law, homeowners who have occupied the property as their primary residence for at least 2 of the previous 5 years exclude up to $250,000 (single filers) or $500,000 (married filing jointly) in capital gains from federal taxation upon liquidation.

Default: $250,000 / $500,000
Amortization Principal Tilt VelocityMonthly Principal vs Interest Ratio

In standard fixed-rate mortgages, early payments consist almost entirely of non-recoverable interest. The breakeven tipping point accelerates once monthly payments shift predominantly toward principal amortization, building true home equity.

Default: Year 7-10 inflection

Pro Tips & Best Practices

Account for Upfront and Exit Friction in Short Horizons

Closing costs when buying (2% to 4%) and realtor commissions when selling (5% to 6%) create an immediate 7% to 10% transaction drag. If your holding timeline is under 4 to 5 years, this transaction friction almost always makes buying financially inferior to renting.

Model the Opportunity Cost of Cash Flow Differentials

A common mistake is only comparing mortgage vs rent. If owning costs $3,500/mo (mortgage, tax, insurance, HOA, maintenance) and renting costs $2,400/mo, the $1,100 monthly savings MUST be invested in equities to make a fair comparison against home equity growth.

Evaluate Standard vs Itemized Tax Deductions Post-TCJA

With the Tax Cuts and Jobs Act raising standard deductions ($14,600 single, $29,200 married) and capping State and Local Taxes (SALT) at $10,000, most new homeowners no longer receive any marginal tax shield from mortgage interest deductions unless the loan balance exceeds $500,000 at 6%+ interest.

Buffer for Unscheduled Capital Expenditures (CapEx)

Unlike rent, where maintenance is capped at zero for the tenant, homeownership incurs lumpy replacement cycles for roofs, HVAC units, and plumbing. Allocate at least 1.0% to 1.5% of the property's value each year into a dedicated liquid emergency maintenance reserve.

Common Gotchas & Troubleshooting

⚠️The calculator displays Never Breaks Even across the entire 30-year span

This occurs when stock market investment return (e.g. 9%+) substantially outperforms home appreciation (e.g. 2%), combined with high recurring HOA and property taxes. Lower the investment return rate to historical inflation-adjusted levels or increase home appreciation to test if a crossover exists.

⚠️Breakeven year shifts drastically when changing filing status from Single to Married

Married status doubles the standard deduction, which often cancels the itemized tax advantage of mortgage interest deductions in the first 5 years, slightly lengthening the time required for buying to break even against renting.

⚠️Total monthly homeowner cash outflow is higher than the purchase price suggests

Verify that annual property tax, homeowner's insurance, and monthly HOA dues are not set to zero. On an average home, non-mortgage escrow expenses represent 30% to 45% of the total monthly cash commitment.

Frequently Asked Questions

How to calculate the breakeven year between renting and buying?▼

The breakeven year is calculated by tracking two parallel cumulative net wealth paths year-by-year: the buyer's net liquidated equity (home market value minus remaining mortgage balance and 6% selling costs) versus the renter's accumulated investment portfolio (initial down payment and monthly savings compounded at the stock market return rate). The breakeven point occurs at the exact month where the buyer's net wealth exceeds the renter's net wealth.

How does the price-to-rent ratio determine whether to buy or rent?▼

The price-to-rent ratio is calculated by dividing the median home purchase price by the annual cost of renting an equivalent home. A ratio under 15 indicates that buying is typically more favorable. A ratio between 16 and 20 signals a moderate market where individual holding duration dictates the outcome. A ratio of 21 or higher strongly favors renting and investing the down payment in diversified index funds.

How does mortgage interest deduction affect rent versus buy comparisons?▼

Homeowners can deduct mortgage interest on the first $750,000 of indebtedness and property taxes up to the $10,000 SALT limit, but only if total itemized deductions exceed the IRS standard deduction ($14,600 for single filers, $29,200 for married couples filing jointly). In high-interest rate environments on loans above $450,000, itemizing provides significant early-year tax refunds that accelerate the breakeven timeline.

Why is renting often considered financially superior for short holding periods?▼

Renting avoids the substantial unrecoverable friction costs of homeownership: 2% to 4% in upfront loan origination, title insurance, and transfer taxes, plus 5% to 6% in broker commissions and closing costs upon resale. In holding periods under 5 years, normal property appreciation is rarely sufficient to offset these 8% to 10% round-trip transaction costs, making renting the lower-risk, wealthier choice.

How should maintenance costs and HOA dues be factored into home buying?▼

Disclaimer: This tool is provided strictly for educational and informational purposes only and does not constitute formal financial advice or a binding loan commitment. Please consult a qualified financial advisor before making decisions. Financial planners recommend budgeting between 1% and 2% of the home's total value annually for routine repairs and long-term capital replacements (such as roof, furnace, and appliances). In condominiums, HOA dues must be added directly to the monthly housing outflow, as HOA fees are completely unrecoverable operational expenses that do not build equity.

Related Tools & Utilities

All Tools →