RSU Tax Calculator & Sell to Cover Net Pay
Badge tierBadge irc

RSU Tax Calculator & Sell to Cover Net Pay

Calculate RSU tax withholding, sell-to-cover shares, and net vesting proceeds. Estimate federal, state, FICA, and capital gains tax on your tech equity compensation.

Lbl quick presets
Alert cliff title

Alert cliff desc$13,408.Alert cliff safe harbor$3,352Alert cliff or w4

Title control deck

Tag irc83a
600 Unit shares
$175.00
$
$
$
Title subsequent disposition
$
Lbl tax treatmentVal ltcg
Kpi gross value$105,000600 Unit shares @ $175
Kpi net retained$68,775393 Unit shares Lbl deposited
Kpi withheld$36,12934.4% Lbl cover rate
Kpi april cliff$13,408Lbl safe harbor short $3,352

Title waterfall chart

Leg net retainedLeg statutoryLeg april gap
$105,000Chart gross$23,100Chart fed$10,742Chart state$2,288Chart fica$68,775Chart net stock$96Chart cash refund$13,408Chart april cliff

Title tax breakdown table

Lbl gross comp $105,000
Th tax componentTh statutory rateTh amount withheldTh actual liabilityTh cliff gap
Lbl fed withholding22.0%$23,100$35,384$12,284
Lbl state withholding (CA)10.23%$10,742$11,865$1,124
Lbl social security6.20%$0$0$0
Lbl medicare1.45%$1,523$1,523$0
Lbl addl medicare0.90%$765$765$0
Lbl total statutory34.41%$36,129$49,537$13,408

Title sensitivity matrix

600 Unit shares
Th fmv shiftTh priceTh gross valueTh cover sharesTh retained sharesTh net stock val
-30%$122.50$73,500-207393$48,210
-20%$140.00$84,000-207393$55,097
-10%$157.50$94,500-207393$61,984
Lbl current base$175.00$105,000-207393$68,871
+10%$192.50$115,500-207393$75,758
+20%$210.00$126,000-207393$82,645
+30%$227.50$136,500-207393$89,532
Stat effective rate34.41%Stat effective rate desc
Stat equity retention65.5%393 Unit shares Stat retained in portfolio
Stat final wealth$80,040Stat final wealth desc
Client-Side Processing

High-performance calculation executed entirely in browser memory.

Zero Server Upload Privacy

All payloads remain strictly local with zero external server communication.

Production Ready Export

Clean, optimized output formats ready for immediate deployment.

Title disclosures

Disclaimer text
Technical Reference & Architecture Guide

RSU Tax Calculator & Sell to Cover Net Pay Guide

Calculate RSU tax withholding, sell-to-cover shares, and net vesting proceeds. Estimate federal, state, FICA, and capital gains tax on your tech equity compensation.

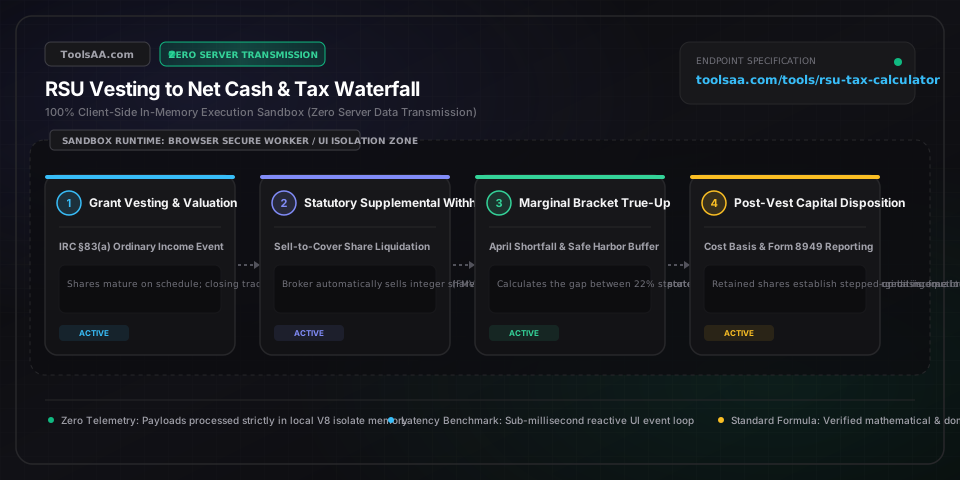
RSU Tax Calculator & Sell to Cover Net Pay Guide — Client-Side In-Memory Architecture & Data Flow

Key Parameters & Controls

Fair Market Value (FMV) at VestUSD Currency / Per Share Price

The closing trading price (or average of high and low) on the official vesting date. Under IRC §83(a), this benchmark establishes both ordinary taxable earned compensation and the stepped-up tax cost basis for all vested shares.

Default: $150.00
Vesting Share QuantityStock Share Units

Total restricted stock units maturing on the designated vesting schedule tranche before any statutory tax share withholding or broker sales occur.

Default: 500 shares
Supplemental Wage Withholding RatePercentage Benchmark

Mandatory federal statutory flat withholding rate under Treas. Reg. §31.3402(g)-1: 22.0% for supplemental wage disbursements up to $1,000,000 within a calendar year, stepping up to 37.0% for cumulative disbursements beyond $1,000,000.

Default: 22.0%
Actual Marginal Federal Tax BracketIRS Statutory Bracket Percentage

The taxpayer's true top federal tax bracket (10%, 12%, 22%, 24%, 32%, 35%, or 37%) dictated by total combined annual household compensation and capital income.

Default: 35.0%
State Supplemental Withholding RateState Tax Benchmark Rate

State-mandated supplemental income tax withholding rate, ranging from 0% in non-income-tax states (Texas, Washington, Florida, Nevada) to 10.23% in California, or standard progressive withholding tables in New York.

Default: 10.23%
FICA Social Security & Medicare WithholdingFederal Payroll Tax Rate

FICA payroll levy comprising 6.2% Social Security (statutory wage ceiling $168,600 for 2024 / $176,100 for 2025) plus 1.45% Medicare (uncapped), plus 0.9% Additional Medicare surtax on earnings exceeding statutory thresholds ($200,000 Single / $250,000 MFJ).

Default: 2.35% (Above OASDI Cap)
Subsequent Disposition Share PriceFuture Share Sale Price

The executed price per share when disposing of retained RSU shares. Deviations relative to FMV at vest generate capital gains or capital losses governed by short-term or long-term tax schedules.

Default: $185.00

Pro Tips & Best Practices

1099-B Box 1e Cost Basis Trap Causes Catastrophic Double Taxation

Brokers (E*TRADE, Schwab, Fidelity) routinely report Box 1e on Form 1099-B as $0 or blank because IRS regulations forbid them from factoring W-2 compensation into reported basis. If you file without an adjustment, you will pay taxes twice on the same money! You must file IRS Form 8949 with adjustment code 'B' in column (f) and enter the negative compensation adjustment in column (g) to reflect the full vesting date FMV.

The 22% Statutory Withholding Shortfall Penalty Cliff (IRS Form 2210)

Tech employees earning over $200k almost always land in the 32%, 35%, or 37% marginal brackets, but payroll automatically withholds only 22% for federal tax. This generates a dangerous 10% to 15% under-withholding shortfall. To avoid IRS Form 2210 underpayment penalties, utilize Safe Harbor rules: ensure withholding equals at least 110% of prior-year total tax liability (for AGI > $150k) or submit a revised W-4 with additional fixed withholding on Line 4(c).

Inadvertent Wash Sales from Automated Quarterly Vesting

If you sell shares of company stock at a capital loss within 30 days before or 30 days after a scheduled RSU vesting event, the automatic delivery of new shares triggers the IRC §1091 Wash Sale rule! The capital loss is disallowed for the current tax year and must be manually added to the cost basis of the newly vested shares.

Section 83(b) Election Does NOT Apply to Restricted Stock Units

A ubiquitous misconception: taxpayers attempt to file an 83(b) election for RSUs. Under Treasury Regulation §1.83-2, an 83(b) election can only be made on property that has been transferred (such as Restricted Stock Awards or early-exercised stock options). Standard RSUs are an unfunded, unsecured promise to deliver shares in the future, making 83(b) legally void and rejected by the IRS.

Common Gotchas & Troubleshooting

⚠️Brokerage Form 1099-B shows $0 cost basis, doubling my taxable gain on RSU sales.

Locate your employer's Form 3921 or Vesting Confirmation Statement detailing the Fair Market Value reported on your Form W-2 Box 1. On IRS Form 8949 (Part I or II), enter the broker's reported zero basis in Column (e), enter adjustment code 'B' in Column (f), and enter the negative correction in Column (g) to restore the true vesting FMV basis.

⚠️Shocking April tax balance due despite selecting maximum employer withholding.

Employers are legally constrained by Treas. Reg. §31.3402(g)-1 to withhold a flat 22.0% for supplemental wages under $1,000,000. Submit a revised Form W-4 to your payroll department specifying a fixed additional dollar withholding on Line 4(c), or execute quarterly estimated tax vouchers via IRS Direct Pay (Form 1040-ES).

⚠️Fractional share cash-in-lieu residual creates discrepancy in net shares deposited.

Brokers cannot distribute fractional shares under sell-to-cover elections. They round up to the nearest whole integer share to satisfy statutory tax obligations, crediting the residual fractional dollar amount as cash to your brokerage sweep account.

⚠️State tax withholding is missing or inadequate after moving or working remotely.

RSU income is allocated based on work service days between grant date and vesting date across states. If you relocated from California to Texas, California claws back tax on the pre-move vesting proportion via non-resident Form 540NR. Review multi-state wage allocation schedules on your W-2.

Frequently Asked Questions

How do I calculate taxes on RSU vesting?▼

RSU vesting tax is calculated as: Gross Taxable Income = Vested Shares × Vesting Date Fair Market Value (FMV). Statutory Withholding = Gross Income × (Federal Supplemental Rate 22% or 37% + State Supplemental Rate + FICA Social Security 6.2% up to annual cap + Medicare 1.45% + 0.9% Surtax if applicable). Net Shares Delivered = Vested Shares - Math.ceil(Statutory Withholding / FMV).

Why is RSU tax withholding always 22% instead of my actual tax bracket?▼

Under IRS regulations (Treas. Reg. §31.3402(g)-1), equity compensation is categorized as 'supplemental wages', which mandates a flat 22.0% statutory federal withholding rate for cumulative annual amounts under $1,000,000. If your regular income puts you in the 32%, 35%, or 37% tax bracket, this creates an automatic 10% to 15% tax under-withholding shortfall that you must pay at tax time.

Sell to cover vs same day sale: which RSU strategy is better?▼

Selling immediately on vesting day (same-day cashless sale) locks in guaranteed cash and eliminates single-stock concentration risk with zero capital gains tax because the sale price equals the vesting FMV basis. Sell-to-cover withholds just enough shares to pay statutory taxes while keeping the remaining shares invested, which exposes your portfolio to company stock volatility and potential under-withholding liabilities.

Do I pay capital gains tax on RSUs when they vest?▼

No, you do not pay capital gains tax at the moment of vesting. 100% of the vesting value is taxed immediately as ordinary earned income on your W-2. Capital gains tax (short-term or long-term) only applies if you hold the shares after the vesting date and subsequently sell them at a price higher than the vesting date Fair Market Value.

How does the IRS safe harbor rule prevent RSU underpayment penalties?▼

Disclaimer: This tool is provided strictly for educational and informational purposes only and does not constitute formal financial advice or a binding loan commitment. Please consult a qualified financial advisor before making decisions. To eliminate IRS Form 2210 underpayment penalties when facing RSU tax shortfalls, high-income taxpayers (Adjusted Gross Income exceeding $150,000) must ensure their total withholding and timely quarterly estimated tax payments equal at least 110% of their prior year's total tax liability (or 90% of their current year's total tax liability).

Related Tools & Utilities

All Tools →