Net Worth Calculator & Wealth Tracker

Net Worth Calculator & Wealth Tracker

Calculate your net worth instantly by tallying liquid assets, investments, real estate, and liabilities. Track debt ratios and forecast wealth growth trajectory.

Select preset
Section profiling
Federal Reserve (SCF 2022/2023)
38 Unit years
55 Unit years
$
$
$
7%
2.5%
$
$
$
$
$
$
$
$
$
Lbl total net worth
$538,600
Lbl realizable net worth: $441,400
Status aaw0.86x Lbl expected net worth
Lbl total assets$1,005,000
Lbl total liabilities$466,400
Lbl liquid net worth$97,600
Lbl solvency ratio53.6%
Health solvent

Commentary solvent

Lbl debt to asset ratio: 46.4%Lbl expected net worth: $627,000

Disclaimer text

Lbl total net worthHealth solvent
$538,600
Lbl solvency ratio: 53.6%
Lbl realizable net worthLbl haircuts active
$441,400
Lbl liquid net worth: $97,600
Lbl stanley danko statusStatus aaw
0.86x
Lbl expected net worth: $627,000
Technical Reference & Architecture Guide

Net Worth Calculator & Wealth Tracker Guide

Calculate your net worth instantly by tallying liquid assets, investments, real estate, and liabilities. Track debt ratios and forecast wealth growth trajectory.

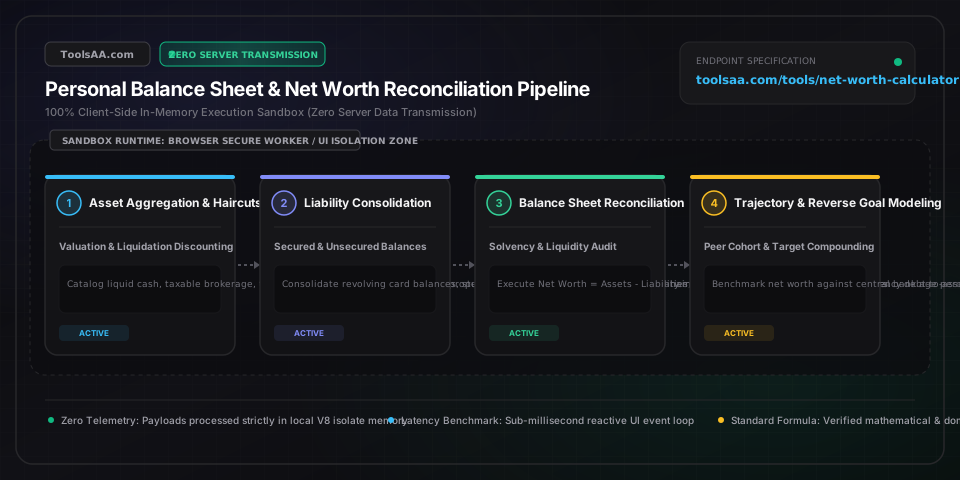
Net Worth Calculator & Wealth Tracker Guide — Client-Side In-Memory Architecture & Data Flow

Key Parameters & Controls

Liquid Reserves & Cash EquivalentsMonetary Capital ($ / € / £ / ¥)

Immediately accessible funds held in checking, FDIC/FSCS-insured high-yield savings (HYSA), money market funds, or short-term certificates of deposit (CDs). Financial planning standards mandate 3 to 6 months of baseline living expenses as an untouched emergency liquidity cushion.

Default: $25,000
Tax-Advantaged Retirement CapitalEquities & Bonds Portfolio ($)

Dedicated retirement accounts including 401(k), 403(b), Traditional/Roth IRAs, and employer pensions. Standard accumulation milestones recommend 1x annual salary by age 30, 3x by 40, 6x by 50, and 8x to 10x by 60.

Default: $120,000
Taxable Brokerage & SecuritiesMarketable Equities ($)

Non-retirement investments in publicly traded individual stocks, index exchange-traded funds (ETFs), mutual funds, and cash management brokerage accounts without statutory withdrawal age penalties.

Default: $45,000
Real Estate Net Realizable EquityTangible Property Asset ($)

Conservative fair-market property valuation minus an estimated 6% to 9% deduction for transaction commissions, staging, legal transfer taxes, and outstanding mortgage debt principal.

Default: $450,000
High-APR Revolving Consumer LiabilitiesUnsecured Debt Obligation ($)

Credit card balances, buy-now-pay-later (BNPL) installment plans, and unsecured signature loans carrying interest rates over 10%. Optimal financial health mandates keeping this metric at $0 statement balance each billing cycle.

Default: $1,500
Long-Term Amortized Secured DebtsCollateralized Debt Obligation ($)

Primary and secondary residential mortgages, home equity lines of credit (HELOC), vehicle financing, and federal student loans backed by amortizing principal schedules and lower relative APRs.

Default: $320,000
Debt-to-Asset Solvency RatioSolvency Percentage (%)

Total liabilities divided by total assets expressed as a percentage. Benchmarks below 30% represent conservative financial fortress balance sheets; 30% to 50% is standard for homeowners; exceeding 70% signals elevated insolvency vulnerability.

Default: 42.5%
Stanley-Danko Wealth Accumulator IndexEfficiency Benchmark Factor (Multiple)

Actual Net Worth divided by Expected Net Worth where Expected Net Worth = (Age * Pre-Tax Income) / 10. A quotient under 0.67 denotes an Under Accumulator of Wealth (UAW); 0.67 to 1.5 represents Average (AAW); 2.0+ signifies a Prodigious Accumulator of Wealth (PAW).

Default: 1.15x
Pro Tips & Best Practices

Haircut Pre-Tax Retirement Accounts for Deferred Income Tax Liabilities

A $500,000 traditional 401(k) or traditional IRA balance does not represent $500,000 in spendable wealth. Because distributions are taxed as ordinary income upon withdrawal, applying a conservative 18% to 24% discount factor provides a more realistic after-tax baseline of your true net worth.

Mark Real Estate to Net Realizable Liquidation Value, Not Algorithmic Zestimates

Never enter the unadjusted peak real estate appraisal as an asset. In a forced liquidation scenario, seller-paid agent commissions (5-6%), transfer taxes (1-2%), seller concessions, and deferred capital improvements reduce your gross home equity by 7% to 10%.

Exclude Depreciating Household Consumer Goods and Term Life Policies

Furniture, consumer electronics, and leased vehicles lose 20% to 50% of their utility value upon purchase and have negligible secondary market liquidation value. Similarly, term life insurance policies carry no cash surrender value and must be treated as $0 on a balance sheet.

Separate Liquid Solvency from Total Paper Net Worth

A multimillion-dollar balance sheet concentrated entirely in illiquid real estate equity or unvested private company stock cannot satisfy short-term cash liabilities. Always track your Liquid Net Worth ((Cash + Public Equities) - Short-Term Debt) to ensure operational solvency during economic downturns.

Common Gotchas & Troubleshooting

⚠️Negative Net Worth Calculation After Factoring Graduate or Medical Student Debt

Having a temporary negative net worth in your twenties or early thirties is standard for specialized professionals investing in high-earning human capital. Focus on managing your debt amortization schedule and monitoring month-over-month net worth velocity rather than the static negative balance.

⚠️Volatile Balance Sheet Fluctuations Driven by Public Equity and Crypto Drawdowns

Avoid recalculating net worth daily during market corrections. Establish a fixed quarterly rebalancing calendar (e.g., March 31, June 30, September 30, December 31) and evaluate your long-term 12-month rolling net worth trend rather than daily market price noise.

⚠️Joint Household Accounts Versus Individual Separate Liability Allocation

When cohabitating or in married households with partially separated finances, avoid double-counting joint mortgage balances against individual liquid checking balances. Either compute a unified household balance sheet or proportionally divide joint equity and debts by ownership percentage.

Frequently Asked Questions

How do I calculate my net worth accurately?▼

Net worth is calculated using the exact formula: Net Worth = Total Assets - Total Liabilities. First, sum all owned assets including liquid cash, investment portfolios, retirement accounts, and real estate market value. Next, sum all debts including mortgages, vehicle financing, student loans, and credit card balances. Subtracting total liabilities from total assets yields your true net worth.

What is a good net worth by age according to official benchmarks?▼

According to the Federal Reserve Survey of Consumer Finances (SCF), the median US household net worth is approximately $39,000 for ages under 35, $135,000 for ages 35-44, $247,000 for ages 45-54, $364,000 for ages 55-64, and $409,000 for ages 65-74. A widely respected wealth benchmark is the Stanley-Danko formula: target net worth equals your current age multiplied by your annual pre-tax household income, divided by 10.

What is the difference between total net worth and liquid net worth?▼

Total net worth encompasses all owned assets including illiquid property, retirement lock-ups, and private equity, minus all liabilities. In contrast, liquid net worth considers only cash equivalents and publicly traded securities that can be converted to cash within 3 to 5 business days without severe liquidation penalties, minus all short-term debts. Liquid net worth measures immediate emergency survival capacity.

Should I include my primary residence and automobile in my net worth?▼

Yes, standard accounting practices include both your primary home and vehicles, provided their corresponding loan balances are simultaneously recorded under liabilities. However, vehicles should be entered at wholesale Kelley Blue Book trade-in value (accounting for rapid depreciation), and home values should deduct estimated 6% to 8% selling and broker commission costs to reflect net realizable value.

What is the Stanley-Danko formula for expected net worth?▼

The Stanley-Danko formula, introduced in 'The Millionaire Next Door', defines Expected Net Worth (ENW) as: ENW = (Age * Pre-Tax Annual Realized Income) / 10. Comparing your actual net worth to this benchmark categorizes you into one of three wealth accumulation tiers: Prodigious Accumulators of Wealth (PAW, net worth at least 2.0x expected), Average Accumulators of Wealth (AAW, net worth between 0.67x and 1.5x expected), and Under Accumulators of Wealth (UAW, net worth below 0.67x expected).

How does debt payoff compare to investing for increasing net worth?▼

Disclaimer: This tool is provided strictly for educational and informational purposes only and does not constitute formal financial advice or a binding loan commitment. Please consult a qualified financial advisor before making decisions. Paying off high-interest debt (such as credit cards with 18% to 28% APR) delivers a guaranteed, risk-free, after-tax return equal to the interest rate avoided, which mathematically outpaces historical stock market equity returns (7% to 10% nominal). Conversely, for low-interest secured debt (such as fixed mortgages under 4% to 5%), allocating surplus cash flow into diversified equity index funds typically generates higher long-term compound net worth due to the compounding equity risk premium over multi-decade horizons.

Related Tools & Utilities

All Tools →