IRS MACRS 27.5-yr straight-line residential depreciation, 1031 Exchange deferral, standard 1.25 DSCR qualification.
Title scorecard
Msg one percent watch
Msg fifty low
Msg dscr fail
Msg break even
Free rental property ROI calculator to analyze real estate cash flow, cap rate, cash-on-cash return, and IRR. Project 30-year appreciation and rental yields.
IRS MACRS 27.5-yr straight-line residential depreciation, 1031 Exchange deferral, standard 1.25 DSCR qualification.
Msg one percent watch
Msg fifty low
Msg dscr fail
Msg break even
Free rental property ROI calculator to analyze real estate cash flow, cap rate, cash-on-cash return, and IRR. Project 30-year appreciation and rental yields.
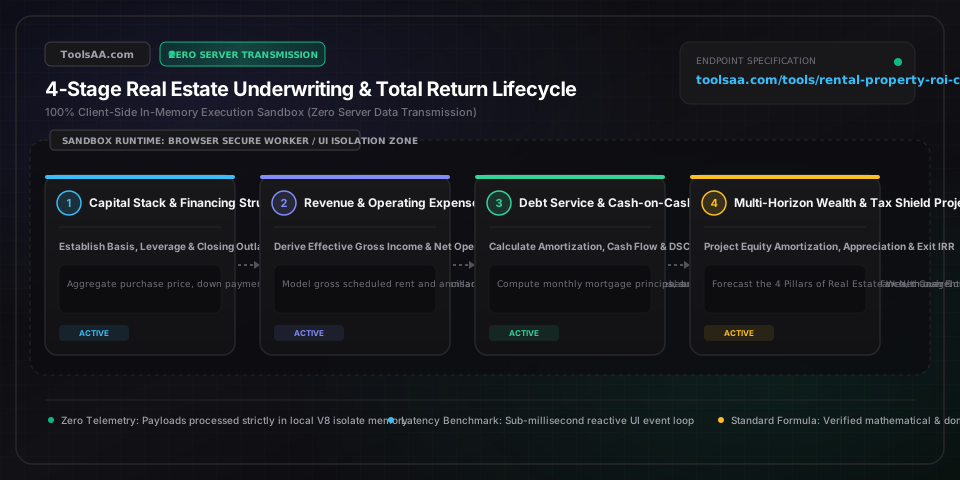
The negotiated contract acquisition price combined with upfront closing costs, financing origination points, pre-tenant renovation expenditures, and initial operating cash reserves. Represents the total initial denominator for calculating Cash-on-Cash Return and Equity Multiples.
The proportion of debt financing relative to total appraised property value. Standard conforming residential investment mortgages mandate 20% to 25% down (75% to 80% LTV). Higher leverage amplifies Cash-on-Cash returns in appreciating markets but increases debt service risk, break-even occupancy pressure, and default vulnerability during downturns.
The total contractual rent potential assuming 100% occupancy at market lease rates, augmented by ancillary revenue streams such as parking spaces, coin-operated laundry facilities, storage lockers, and non-refundable pet fees. Forms the baseline top-line figure before vacancy discounts.
The expected percentage of annual gross income lost to physical unoccupied days between tenant leases, eviction turnover friction, and uncollectible delinquent rent. Institutional underwriting models benchmark stabilized residential vacancy between 4.0% and 8.0% depending on local metropolitan rental demand and job growth dynamics.
The pure operational earnings generated by the real estate asset, calculated by subtracting all legitimate operating expenditures (property taxes, hazard insurance, management fees, maintenance allowances, CapEx reserves, HOA dues) from Effective Gross Income. Critically, NOI is strictly unlevered and excludes mortgage debt service, income taxes, and book depreciation.
The ratio of an asset's annual Net Operating Income to its total acquisition price [Cap Rate = (Annual NOI / Purchase Price) * 100]. Provides an un-leveraged measure of property profitability independent of mortgage financing terms. Prime gateway city properties typically trade at 4.0% to 5.5% cap rates, while secondary and tertiary cash-flow markets range from 6.5% to 9.5%+.
The annual pre-tax cash flow pocketed by the investor expressed as a percentage of total actual cash invested out-of-pocket [CoC = (Annual Cash Flow Before Taxes / Total Initial Cash Outlay) * 100]. The primary metric real estate investors utilize to compare cash distributions directly against dividend yields, private equity, or Treasury bond coupons.
The ratio of annual Net Operating Income to annual principal and interest mortgage obligations [DSCR = Annual NOI / Annual Debt Service]. Commercial and portfolio lenders mandate a minimum DSCR threshold of 1.20x to 1.25x to ensure an adequate operational cash cushion exists to absorb tenant vacancies without loan default.
The annualized compound discount rate that sets the Net Present Value (NPV) of all projected interim net cash flows plus terminal net sale proceeds exactly equal to zero. Integrates cash flow yields, loan principal amortization paydown, and terminal capital appreciation into a single comprehensive lifecycle performance metric.
Under US Internal Revenue Code Section 168, residential rental improvements (excluding land allocation) are depreciated straight-line over a statutory recovery period of 27.5 years (3.636% per annum). This non-cash paper expense frequently shelters rental cash distributions from current income taxes or generates passive tax losses to offset other passive gains.
Novice investors routinely lump all property upkeep into a single generic 5% maintenance bucket, creating devastating cash shortfalls when high-ticket mechanical systems fail. Professional underwriters strictly bifurcate operating expenses: allocate 4% to 6% of gross rent for minor operational repairs (plumbing leaks, locksmiths, drywall patching), and maintain an independent, dedicated 5% to 8% Capital Expenditure (CapEx) sinking fund reserved exclusively for long-cycle replacements—such as roofs ($8,000-$15,000 every 20 years), HVAC heat pumps ($5,000-$9,000 every 12 years), and water heaters ($1,200-$2,000 every 8 years).
A high 10% Cap Rate in a declining Rust Belt industrial submarket is rarely superior to a 5.5% Cap Rate in a high-demand Sunbelt tech hub. Cap Rate is strictly an unleveraged valuation multiplier that entirely ignores debt financing, local economic appreciation velocity, and capital preservation. High Cap Rate properties typically carry older physical infrastructure, elevated tenant turnover friction, and flatter long-term rent appreciation, while lower Cap Rate institutional assets generate substantial total return via equity multiple expansion and compounding rental rate hikes.
While annual depreciation provides a powerful non-cash tax shield during ownership, selling an investment property triggers federal depreciation recapture taxed at a flat statutory rate of up to 25% under IRC Section 1250, alongside ordinary federal and state capital gains taxes. To build generational wealth without immediate tax drag, utilize an IRC Section 1031 Tax-Deferred Exchange: identify replacement properties within 45 calendar days of closing, and transfer 100% of net equity and debt into the new real estate asset within 180 calendar days.
You cannot legally depreciate land, only physical building structures and site improvements. While standard tax preparers often default to an arbitrary 20% land / 80% building split, review your county property tax assessment card or commission a professional appraisal. In markets where land value represents only 10% to 15% of total purchase price, allocating 85% to 90% to depreciable building improvements materially increases your annual non-cash tax write-off, shielding thousands of dollars in rental income from income taxes.
A rental property generating an 8% Cash-on-Cash return demands active landlord responsibilities: lease drafting, tenant screening, contractor oversight, and localized regulatory compliance. Evaluate your total investment hurdle rate: if passive S&P 500 index funds historically deliver ~9.8% annualized nominal return with absolute liquidity and zero management overhead, your target real estate deal must achieve an unleveraged total IRR of 12% to 15%+ (combining cash distributions, mortgage principal amortization, tax sheltering, and capital appreciation) to justify illiquidity and active operational risk.
In many fiscal jurisdictions, properties held by previous owners for decades benefit from statutory property tax caps or outdated municipal assessments. Upon sale, the local tax assessor reassesses the property based on the newly recorded purchase price. An investor relying on historical property tax figures ($2,000/yr) can experience a sudden jump to $5,500/yr, transforming a positive monthly cash flow into a recurring deficit. Always calculate projected property taxes based on your actual contract purchase price multiplied by the local millage rate rather than relying on the seller's historical tax bills.
Calculators that divide annual cash flow exclusively by the down payment percentage produce dangerously inflated Cash-on-Cash returns. True initial invested capital must incorporate lender origination points (1% to 2%), appraisal and title fees ($3,000 to $6,000), immediate pre-lease tenant make-ready renovations ($5,000 to $25,000), and an initial 3-month operating reserve. Always sum Down Payment + Closing Costs + Rehab Outlay + Working Reserves as the true denominator.
A pro-forma claiming 9.5% Cap Rate based on 100% occupancy often masks severe economic vacancy. Every physical tenant changeover costs approximately 1.5 to 2.5 months of gross rent: 1 month of physical unleased vacancy, a professional leasing agent placement commission (50% to 100% of one month's rent), professional carpet cleaning, fresh paint, and locksmith fees. Underwrite at minimum an 8.33% vacancy allowance (equivalent to 1 month vacancy per year) for single-family rentals to reflect real-world turnover realities.
Investors holding adjustable-rate mortgages (ARMs) or commercial balloon notes that reset after 5 or 7 years can see debt service expand by 30% to 50% during monetary tightening cycles, crushing cash flow and breaching loan covenants. Protect solvency by stress-testing your deal: ensure the property maintains a minimum 1.15x DSCR even if interest rates rise by 200 to 300 basis points, or secure 30-year fixed-rate financing to permanently lock in borrowing costs.
To calculate Cash-on-Cash return (the standard annual cash ROI metric), divide your annual Pre-Tax Cash Flow by your Total Cash Invested: [Cash-on-Cash Return % = (Annual Net Cash Flow / Total Cash Invested) * 100]. For example, if you purchase a rental property for $300,000 by putting down $60,000 (20%), paying $6,000 in closing costs, and spending $4,000 on initial paint and renovations, your Total Cash Invested is $70,000. If the property generates $2,400 monthly rent ($28,800/yr), incurs $8,800 in annual operating expenses (taxes, insurance, maintenance, vacancy), and requires $14,400 in annual mortgage debt service, your Annual Cash Flow is $5,600 ($28,800 - $8,800 - $14,400). Your Cash-on-Cash return is ($5,600 / $70,000) * 100 = 8.0%.
A 'good' capitalization rate varies significantly by market tier and asset risk profile, but institutional benchmarks generally follow three categories: Prime Gateway Metros (Tier 1 cities like New York, Los Angeles, Seattle, or London) typically trade at 4.0% to 5.5% cap rates due to intense institutional demand, low default risk, and high long-term appreciation potential; Secondary Suburban Growth Hubs (Tier 2 markets like Atlanta, Dallas, Phoenix, or Tampa) typically yield 6.0% to 7.5% cap rates offering a balanced mix of current yield and capital growth; Tertiary and Rust Belt Cash Flow Markets (Tier 3 markets like Cleveland, Memphis, or Indianapolis) often trade at 8.0% to 10.0%+ cap rates to compensate investors for flatter appreciation, older housing stock, and higher tenant management friction.
The fundamental difference is that Cap Rate measures the unleveraged operational profitability of the property itself, whereas Cash-on-Cash Return measures the levered cash yield on your actual out-of-pocket equity investment. Cap Rate is calculated as [Net Operating Income (NOI) / Total Purchase Price] and completely ignores mortgages, down payments, and debt service—making it ideal for comparing the intrinsic profitability of different properties regardless of how they are financed. Conversely, Cash-on-Cash Return is calculated as [Annual Cash Flow After Debt Service / Actual Cash Invested], reflecting the direct financial impact of mortgage interest rates, down payment leverage, and loan amortization on the investor's personal bank account.
The 1% Rule and 50% Rule are institutional screening heuristics used for rapid top-of-funnel deal evaluation. The 1% Rule states that a rental property should generate at least 1.0% of its total acquisition price in gross monthly rent to achieve positive cash flow: for instance, a $250,000 house should rent for at least $2,500 per month. The 50% Rule states that approximately 50% of an investment property's Gross Operating Income will be consumed by non-mortgage operating expenses (property taxes, insurance, management fees, maintenance, vacancy, and CapEx reserves) over the long run. If a property generates $3,000/month, the 50% rule estimates $1,500 in operating expenses, leaving $1,500 in Net Operating Income (NOI) to service mortgage debt and generate investor cash flow.
Under US Internal Revenue Code Section 168 (and comparable international depreciation regimes like UK Capital Allowances or German AfA), real estate investors can deduct the physical wear-and-tear of residential buildings over a statutory 27.5-year recovery period using straight-line depreciation. Because land does not depreciate, you subtract land value (typically 20%) from the purchase price to find the depreciable basis: for a $300,000 property with $60,000 land, the depreciable building basis is $240,000, creating an annual non-cash tax deduction of $8,727.27 ($240,000 / 27.5). If your rental generates $6,000 in net taxable operating cash flow, the $8,727 depreciation deduction completely offsets this income, allowing you to pocket the $6,000 100% tax-free while reporting a $2,727 paper passive loss to shelter other passive income.
Disclaimer: This tool is provided strictly for educational and informational purposes only and does not constitute formal financial advice or a binding loan commitment. Please consult a qualified financial advisor before making decisions. To calculate the Maximum Allowable Offer (MAO) for a target 10% Cash-on-Cash return, solve inversely by equating target cash flow to 10% of total cash invested: [Target Annual Cash Flow = Target CoC * (Down Payment + Closing Costs + Rehab)]. Net cash flow is defined as Effective Gross Income minus Operating Expenses minus Debt Service: [EGI - OpEx - Loan Amount * Mortgage Constant = Target CoC * (Price * Down Payment % + Closing Costs + Rehab)]. Expressing Loan Amount as [Price * (1 - Down Payment %)], group all Price variables to solve directly: [Max Purchase Price = (EGI - OpEx - Target CoC * (Closing Costs + Rehab)) / (Target CoC * Down Payment % + (1 - Down Payment %) * Annual Mortgage Constant)]. For an unleveraged all-cash acquisition, the reverse formula simplifies directly to [Max Price = (EGI - OpEx) / Target Cap Rate].
Calculate Roth IRA growth and compound interest with annual IRS limits, catch-up age rules, inflation drag, and tax-free retirement withdrawal forecasts.
Calculate single and multiple event probabilities, odds ratios, conditional Bayes outcomes, and independent or mutually exclusive event series with steps.
Solve proportion and ratio equations (A/B = C/D) instantly. Find unknown X values, simplify ratios, scale recipes, and calculate direct or inverse proportions.
Calculate daily protein intake by body weight, activity level, and fitness goals. Find your optimal grams per day for muscle building, fat loss, and maintenance.
Calculate gas mileage and MPG fuel economy instantly. Track trip gas cost, compare US and UK gallons, convert L/100km, and estimate annual commute fuel spending.
Calculate engine horsepower from torque and RPM, or convert wheel horsepower to crank BHP with drivetrain loss. Estimate quarter-mile ET and speed instantly.