Short title

Paycheck Tax Calculator & Take Home Pay

Calculate paycheck net take-home pay after federal, state, FICA taxes, and 401(k) deductions. Free salary tax estimator with reverse gross-up and W-4 tools.

Lbl load preset
Lbl compensation type
$95,000.00
$
Lbl tax regime
Lbl w4 settings
Lbl pre tax deductions
5% ($4,750.00)
Tab cockpit
Lbl net pay per check
$2,547.22
Lbl gross per check $3,653.85
Lbl annual net pay$66,227.74Lbl take home ratio 69.7%
Lbl effective rate23.4%
Lbl marginal rate39.0%
Lbl federal tax$434.62$11,300.00
Lbl total fica$274.22$7,129.80
Lbl take home ratio69.7%
Lbl effective rate23.4%
0%25%50%+
Lbl marginal rate:39.0%
Lbl net pay per check
$2,547.22
Lbl federal tax
$434.62
Lbl total fica
$274.22
Lbl state tax
$145.86
Lbl pre tax total
$251.92
Lbl post tax total
$0.00
Lbl gross per check100%
Lbl net pay per check$2,547.22
Lbl annual net pay$66,227.74
Lbl effective rate23.4%
Lbl marginal rate39.0%
Lbl total taxes$22,222.26
Lbl take home ratio69.7%
Disclaimer titleDisclaimer text
Technical Reference & Architecture Guide

Paycheck Tax Calculator & Take Home Pay Guide

Calculate paycheck net take-home pay after federal, state, FICA taxes, and 401(k) deductions. Free salary tax estimator with reverse gross-up and W-4 tools.

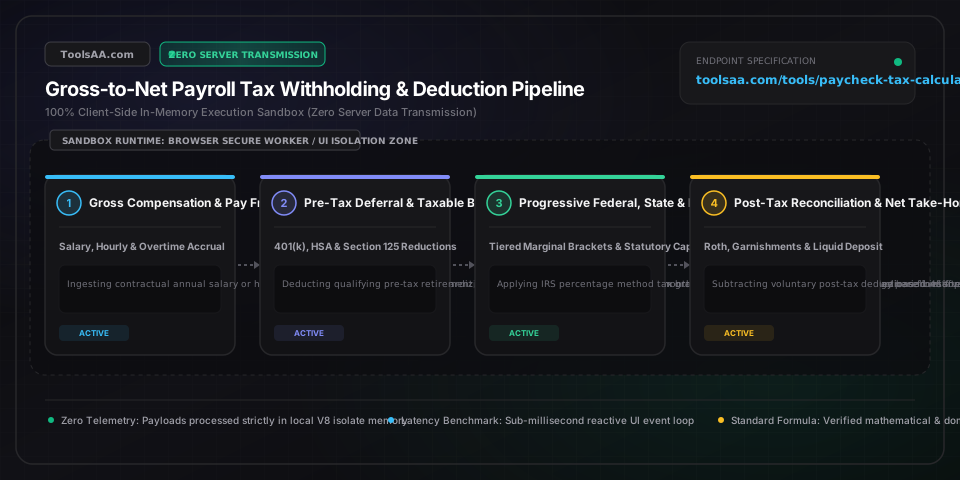
Paycheck Tax Calculator & Take Home Pay Guide — Client-Side In-Memory Architecture & Data Flow

Key Parameters & Controls

Gross Pay (Gross Wages)Currency Monetary Amount ($ USD / Period or Annual)

The total compensation earned by an employee prior to any mandatory payroll tax withholdings, statutory contributions, or voluntary benefit deductions. For salaried employees, this is annual base salary divided by annual pay periods; for hourly employees, regular hours times base rate plus overtime hours times premium rate.

Default: $75,000.00 Annual ($2,884.62 Bi-Weekly)
Federal Income Tax Withholding (FIT)Progressive Tiered Tax Ratio (% / Bracketed Sum)

The statutory federal income tax deducted from employee wages by employers under Internal Revenue Code Section 3402, calibrated according to Form W-4 inputs, active filing status standard deductions, and the 7 federal progressive tax brackets (10% to 37%).

Default: Calculated via 2024/2025 IRS Percentage Method Tables
Social Security Tax (OASDI)Statutory FICA Wage Tax (6.20% with Wage Base Cap)

Old-Age, Survivors, and Disability Insurance tax mandated under FICA at a fixed employee rate of 6.20% (matched by 6.20% from employer). Withholding halts once employee cumulative annual wages reach the statutory wage base limit ($168,600 in 2024, $176,100 in 2025).

Default: 6.20% of FICA Taxable Wages (Max $10,453.20 in 2024)
Medicare Tax & Additional Medicare TaxUncapped Statutory FICA Tax (1.45% + 0.90% Surcharge)

Hospital Insurance tax levied at 1.45% on all employee earnings with no annual wage ceiling. Under the Affordable Care Act, an Additional Medicare Tax of 0.90% (total 2.35%) applies to compensation exceeding statutory thresholds ($200,000 for Single/HOH, $250,000 for MFJ).

Default: 1.45% on all wages (+0.90% over $200k/$250k threshold)
State Income Tax (SIT)State Statutory Withholding (0.00% to 13.30%)

Income tax withheld for state government jurisdictions. Nine states levy no tax on earned wages (AK, FL, NV, NH, SD, TN, TX, WA, WY). Others impose flat statutory rates (e.g. PA 3.07%, IL 4.95%) or graduated progressive bracket tiers (e.g. CA 1.0% to 13.3%, NY 4.0% to 10.9%).

Default: Jurisdiction-Dependent (e.g., California Progressive / Texas 0.00%)
Pre-Tax Retirement Deductions (401k / 403b / HSA)Pre-Tax Elective Deferral ($ USD or Percentage %)

Voluntary contributions diverted into qualified retirement accounts (Traditional 401k, 403b, 457) or health accounts (HSA, FSA) directly before federal and state income taxes are calculated, shielding income and reducing effective tax liability.

Default: 5.00% of Gross Pay (Annual IRS Limit $23,000 for 401k in 2024)
Net Take-Home PayNet Disposable Liquid Paycheck ($ USD / Period)

The final liquid compensation deposited into the employee's bank account after subtracting all statutory federal, FICA, state, and local taxes, as well as voluntary pre-tax and post-tax benefit withholdings from gross wages: Net Pay = Gross Pay - Total Taxes - Total Deductions.

Default: Calculated Result (typically 68% to 78% of Gross Pay)
Effective Tax Rate vs Marginal Tax RateComparative Tax Quotient Percentage (%)

Marginal tax rate is the tax percentage applied to the very last dollar of income earned within your highest tax bracket. Effective tax rate is the true average percentage of your total income paid in taxes: Effective Rate (%) = (Total Tax Liability / Gross Income) * 100.

Default: Effective Rate typically 12% to 24% vs Marginal 22% to 35%
Pro Tips & Best Practices

The Pre-Tax 401(k) Cushion: Why Saving 100 Dollars Only Costs 76 Dollars in Take-Home Pay

Because contributions to a Traditional 401(k), 403(b), or Health Savings Account (HSA) are deducted from your gross pay before federal and state income taxes are calculated, every dollar contributed reduces your taxable income in your highest marginal bracket. For an employee in the 22% federal bracket and 5% state tax bracket, contributing $100 to retirement only reduces actual paycheck take-home cash by $73 to $78, while granting you $100 in compounding retirement assets.

The Social Security Wage Base Cliff: Why Late-Year Paychecks Suddenly Increase for High Earners

FICA Social Security tax (6.20%) only applies to earned income up to the statutory wage base limit ($168,600 for 2024, projected $176,100 for 2025). Once your cumulative year-to-date earnings surpass this threshold (often in September or October for high-earning professionals), employers immediately stop deducting the 6.20% Social Security tax, resulting in an automatic 6.20% raise in take-home pay for the remaining pay periods of the calendar year.

The Form W-4 Step 2 Dual-Earner Trap: How Married Couples Accidentally Under-Withhold Taxes

If both spouses work or you hold multiple jobs, checking 'Married Filing Jointly' on your W-4 without completing Step 2 (Multiple Jobs) instructs each employer to apply the full married standard deduction ($29,200) and lower tax brackets to each salary independently. This results in significant under-withholding throughout the year and an unexpected tax bill in April. Check the Step 2(c) box on both spouses' W-4s or use Step 4(c) to designate extra withholding per pay period.

Bi-Weekly vs Semi-Monthly Pay Cadence: The 'Three-Paycheck Month' Budgeting Windfall

Bi-weekly pay schedules result in 26 paychecks per year (every two weeks), whereas semi-monthly schedules produce exactly 24 paychecks (twice monthly, typically the 1st and 15th). Employees paid bi-weekly receive two months every calendar year containing three paychecks rather than two. If your household budget is calibrated to two paychecks per month, these two 'magic' third paychecks can be directed 100% toward debt repayment, emergency funds, or investments.

Common Gotchas & Troubleshooting

⚠️First paycheck of a new job is substantially smaller than the amount estimated by standard salary calculations

Check your paystub's pay period start and end dates. New hires frequently start mid-pay-period, receiving a prorated paycheck reflecting fewer days worked. Additionally, upfront one-time benefit deductions or initial benefit enrollment fees may be deducted all at once. Review the gross pay line to confirm your contractual salary rate and verify that prorated hours match actual days on the job.

⚠️Net take-home pay decreased in January despite receiving an annual merit raise or salary promotion

Several annual factors reset in January: (1) Social Security tax (6.2%) resumes if you exceeded the wage base cap in the previous year; (2) Annual health, dental, and vision benefit premiums frequently adjust upward for the new plan year; (3) You may have increased your 401(k) contribution percentage under auto-escalation; or (4) Annual statutory inflation adjustments to IRS standard deductions and tax bracket thresholds changed withholding formulas.

⚠️Employer withheld excessive or zero state income tax after relocating to a new state or working remotely

State tax withholding is governed by physical work location nexus and telecommuting reciprocity agreements. If your employer's payroll department still has your prior state registered, they will remit taxes to the wrong jurisdiction. Submit an updated state employee withholding certificate (e.g., DE 4 in California, IT-2104 in New York) to your HR or payroll administrator immediately to establish correct state residency withholding.

⚠️Supplemental bonus check had significantly higher tax withheld compared to regular bi-weekly salary

The IRS mandates that supplemental wages (bonuses, commissions, stock vestings) be withheld using either the statutory flat rate of 22% (or 37% on amounts exceeding $1 million) or the aggregate method. When employers use the aggregate method, payroll software treats the one-time bonus as if you earn that elevated amount every single pay period, artificially pushing withholding into the 32% or 35% bracket. Any excess withheld will be refunded when filing your annual Form 1040.

Frequently Asked Questions

How do I calculate my net take-home pay from my gross annual salary?▼

To calculate net take-home pay, start with gross pay per pay period (annual salary divided by number of pay periods, such as 26 for bi-weekly). Subtract pre-tax deductions (Traditional 401k, health insurance premiums, HSA). From the remaining taxable wages, subtract Federal Income Tax withholding based on IRS percentage method tables, FICA taxes (6.2% Social Security up to cap plus 1.45% Medicare), State Income Tax, and local city taxes. Finally, subtract any post-tax deductions (Roth 401k, garnishments) to arrive at net take-home pay.

What is the difference between marginal tax rate and effective tax rate on a paycheck?▼

Your marginal tax rate is the top tax bracket that applies to your highest dollar of taxable income (e.g., 22% or 24%). In contrast, your effective tax rate is the true average percentage of your total gross income paid in taxes across all brackets: Total Taxes Paid divided by Gross Income. Because the US uses a progressive tax system where lower income tiers are taxed at 0% (standard deduction), 10%, and 12%, your effective tax rate is always substantially lower than your top marginal tax bracket.

How does contributing to a 401k or HSA affect my paycheck take-home pay?▼

Contributions to a Traditional 401(k), 403(b), or Health Savings Account (HSA) are pre-tax, meaning they reduce your taxable gross income before federal and state income taxes are calculated. If your combined federal and state marginal tax rate is 27%, contributing $100 to your 401(k) saves you $27 in taxes, meaning your actual take-home pay only drops by $73. Furthermore, HSA contributions made through Section 125 payroll cafeteria plans are also exempt from 7.65% FICA taxes, saving you even more.

Why is Social Security tax capped but Medicare tax is uncapped?▼

Under the Federal Insurance Contributions Act (FICA), Social Security benefits paid out in retirement are tied to a maximum statutory benefit formula, and therefore the tax funding it is capped at an annual wage base limit ($168,600 for 2024, projected $176,100 for 2025). Earnings above this threshold owe 0% Social Security tax. Conversely, Medicare Hospital Insurance provides universal healthcare coverage for retirees and has no wage ceiling; every dollar earned owes 1.45% Medicare tax, with an extra 0.9% Additional Medicare Tax on high earners over $200,000.

How do pay frequencies like bi-weekly, semi-monthly, and monthly differ in take-home pay?▼

Annual net take-home pay remains virtually identical across pay frequencies for the same gross salary, but individual paycheck sizes and schedules differ. Bi-weekly pay occurs every two weeks resulting in 26 paychecks per year (including two months with three paychecks). Semi-monthly pay occurs twice a month (typically the 1st and 15th) producing 24 paychecks per year, making each check ~8.3% larger than a bi-weekly check. Monthly pay provides 12 paychecks per year, requiring careful monthly budgeting for regular bills.

How does the IRS Form W-4 affect how much tax is withheld from my paycheck?▼

Disclaimer: This tool is provided strictly for educational and informational purposes only and does not constitute formal financial advice or a binding loan commitment. Please consult a qualified financial advisor before making decisions. Form W-4 instructs your employer's payroll software on how much federal income tax to withhold. Step 1 sets your filing status and baseline standard deduction. Step 2 adjusts for multiple jobs or a working spouse to prevent under-withholding. Step 3 claims dependent child tax credits ($2,000 per child under 17), directly reducing annual withholding. Step 4 allows you to report non-wage income, claim itemized deductions exceeding the standard deduction, or request extra dollar withholding per paycheck to avoid tax-time surprises.

Related Tools & Utilities

All Tools →